Nepal Stocks Clear Resistance as Banks Lead Liquidity-Fueled Rally
NEPSE cleared the 2,629–2,633 resistance zone as banking stocks drove a broad, high-volume rally erasing the market’s entire August drawdown.
Markets Today
The 30-Second Read
NEPSE closed 2,647.22, up 22.85 (+0.87%) clean through the 2,629–2,633 zone that rejected the market on Tuesday. The index is now 2.86 points from where this coverage began on 7 August. The entire −4.81% drawdown has been erased.
Banking led at +1.59% and took the tape. Six banks in the volume top ten, four in the turnover top five. Kumari Bank +4.13% on Rs 32.14 crore; Laxmi Sunrise +3.31% on Rs 27.16 crore. This is the first genuine sector-wide bank move of the coverage.
Volume hit 2.13 crore units, the highest of the coverage. Turnover Rs 6.75 arab, second-highest. Transactions 64,072, second-highest. Breadth 2.65 (196 up, 74 down).
Snow Rivers rose 13.66%, the day's best, three sessions after proposing a 10.5263% dividend. The dividend thread is now 5 for 5 on announcement-day-or-shortly-after moves.
Hathway Investment closed limit-down at −15.00% to 499.80, the biggest single-name decline of the coverage. Down 17.9% in two sessions and 18.0% from its 11 September high, with no public explanation.
The liquidity engine has a name: remittance inflows rose 21.2% to Rs 215.05 billion in the first month of FY 2026/27. That is more than the entire Rs 166.50 billion margin-lending book, arriving in thirty days.
But the trade deficit widened 24.9% to Rs 148.74 billion in the same month, and remittance growth is decelerating hard — 21.2% against 29.9% a year earlier and just 10.2% in dollar terms against 25%.
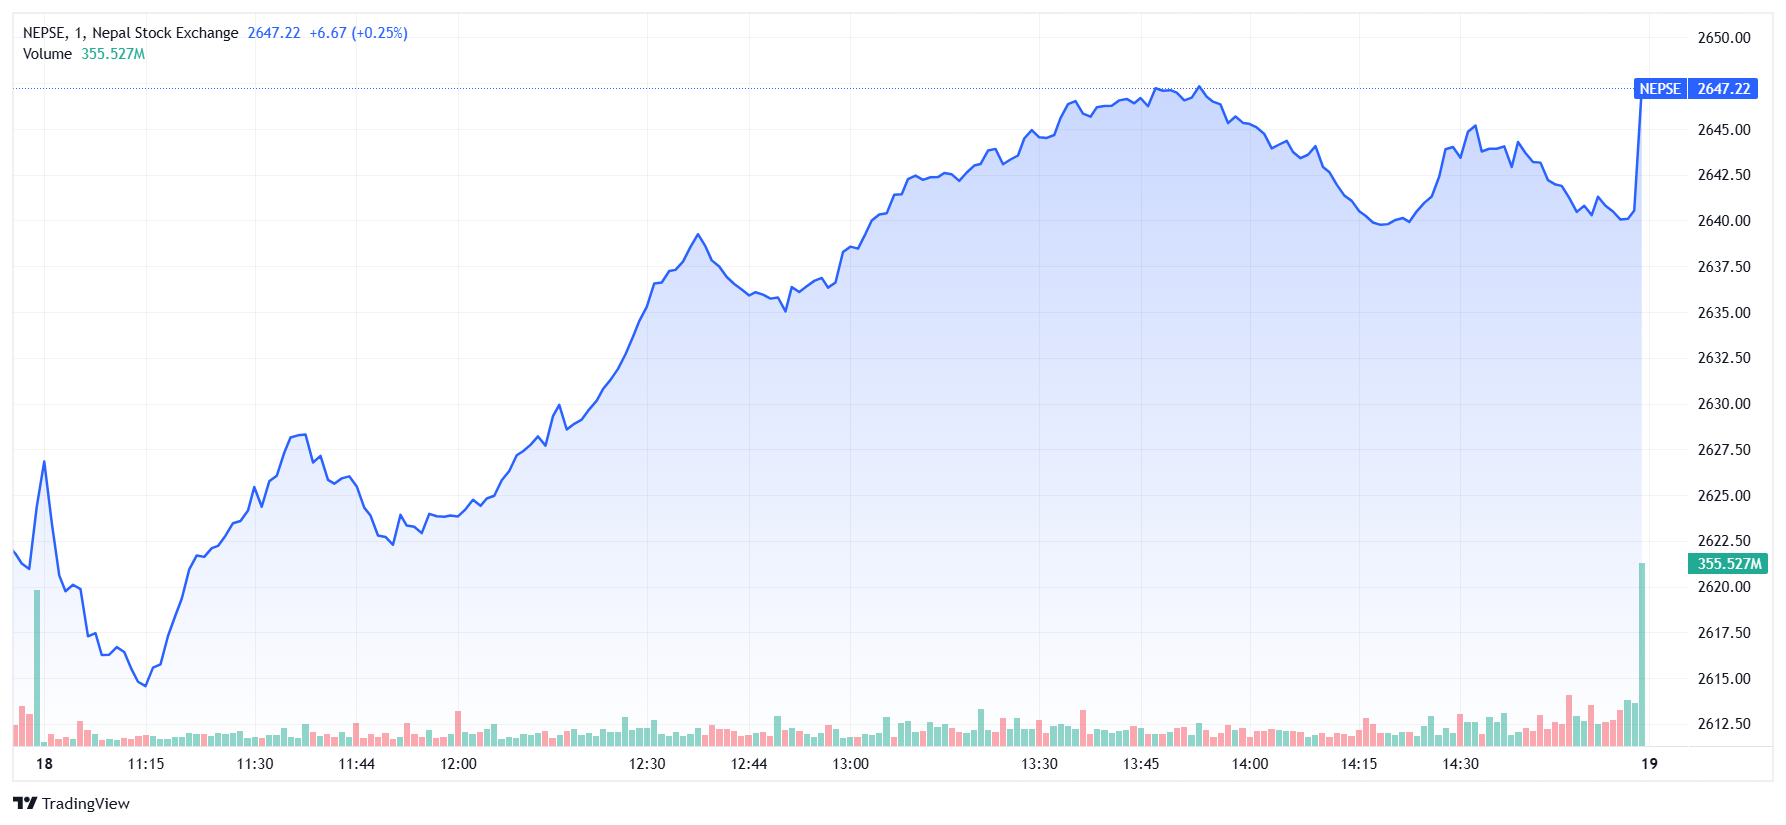
Yesterday's report put the market 4.64 points below the band that had turned it back on Tuesday and said a second attempt would be more meaningful than the first because it would come without a record-breadth blow-off behind it.
It cleared it and it did so on bank buying.
NEPSE closed 2,647.22, up 22.85 points (+0.87%) on Rs 6.75 arab, 2.13 crore units and 64,072 transactions across 345 scrips. Advancers 196, decliners 74, unchanged 12 an A/D of 2.65.
The index is 2.86 points below the 7 August starting level of 2,650.08. Across twenty-six sessions this market fell 136.66 points to a coverage low of 2,513.42 on 31 August and has now recovered 133.80 of them (+5.32%). The drawdown this report was built to document is, as of today, gone.
Banking is the story and it is new. The sub-index rose 1.59%, the best of thirteen, and the participation was not selective: KBL +4.13%, LSL +3.31%, PCBL +2.86%, NBL +2.77%, NMB +2.54%, CZBIL +2.45%, NIMB +2.03%, ADBL +1.72%, SANIMA +1.56%, MBL +1.52%, PRVU +1.39%, GBIME +1.05%. Only SBL lagged at +0.20% and NABIL at +0.52%.
Six banks occupied the volume top ten: KBL, LSL, GBIME, SBL, NBL, MBL and four took the turnover top five. Kumari Bank alone did Rs 32.14 crore (4.8% of the market) on 14.26 lakh shares. Every prior rally in this coverage was carried by hydropower thin prints or a single name taking 11% of the tape. This one was carried by the largest, most liquid institutions on the exchange.
And the money is real. Volume of 2.13 crore units is the highest of the coverage, beating 15 September's 2.04 crore. Turnover at Rs 6.75 arab is second only to that session's Rs 8.29 arab and up Rs 1.25 billion from Thursday. Four consecutive sessions above Rs 5 arab: 8.29 → 5.39 → 5.50 → 6.75.
Eleven of thirteen sub-indices rose. Only Finance (−0.02%) and Others declined both marginally.
The one violent move was HATHY, limit-down at −15.00%. That completes a collapse from 609.00 on 11 September to 499.80, −18.0% in a name that rose 5.56% on announcing a Rs 40 crore investment into a sugar mill and hydropower. No public explanation has surfaced.
Index Snapshot
Index | Close | Change | % |
|---|---|---|---|
NEPSE | 2,647.22 | +22.85 | +0.87% |
Sensitive | ~469.00 | +5.32 | ~+1.15% |
Float | 182.46 | +1.87 | +1.03% |
Sensitive Float | ~158.48 | +1.90 | ~+1.21% |
Turnover Rs 6.75 arab
Volume 2.13 crore units
Transactions 64,072
Scrips traded 345
Every measure of the large-cap, float-adjusted market outperformed the headline index. Sensitive Float at roughly +1.21% and Sensitive at roughly +1.15% against NEPSE's +0.87%. That is what a bank-led rally looks like from the index side and it is the second time in the coverage that the quality end has led, the first being 7 September.
Sectoral Indices Performance
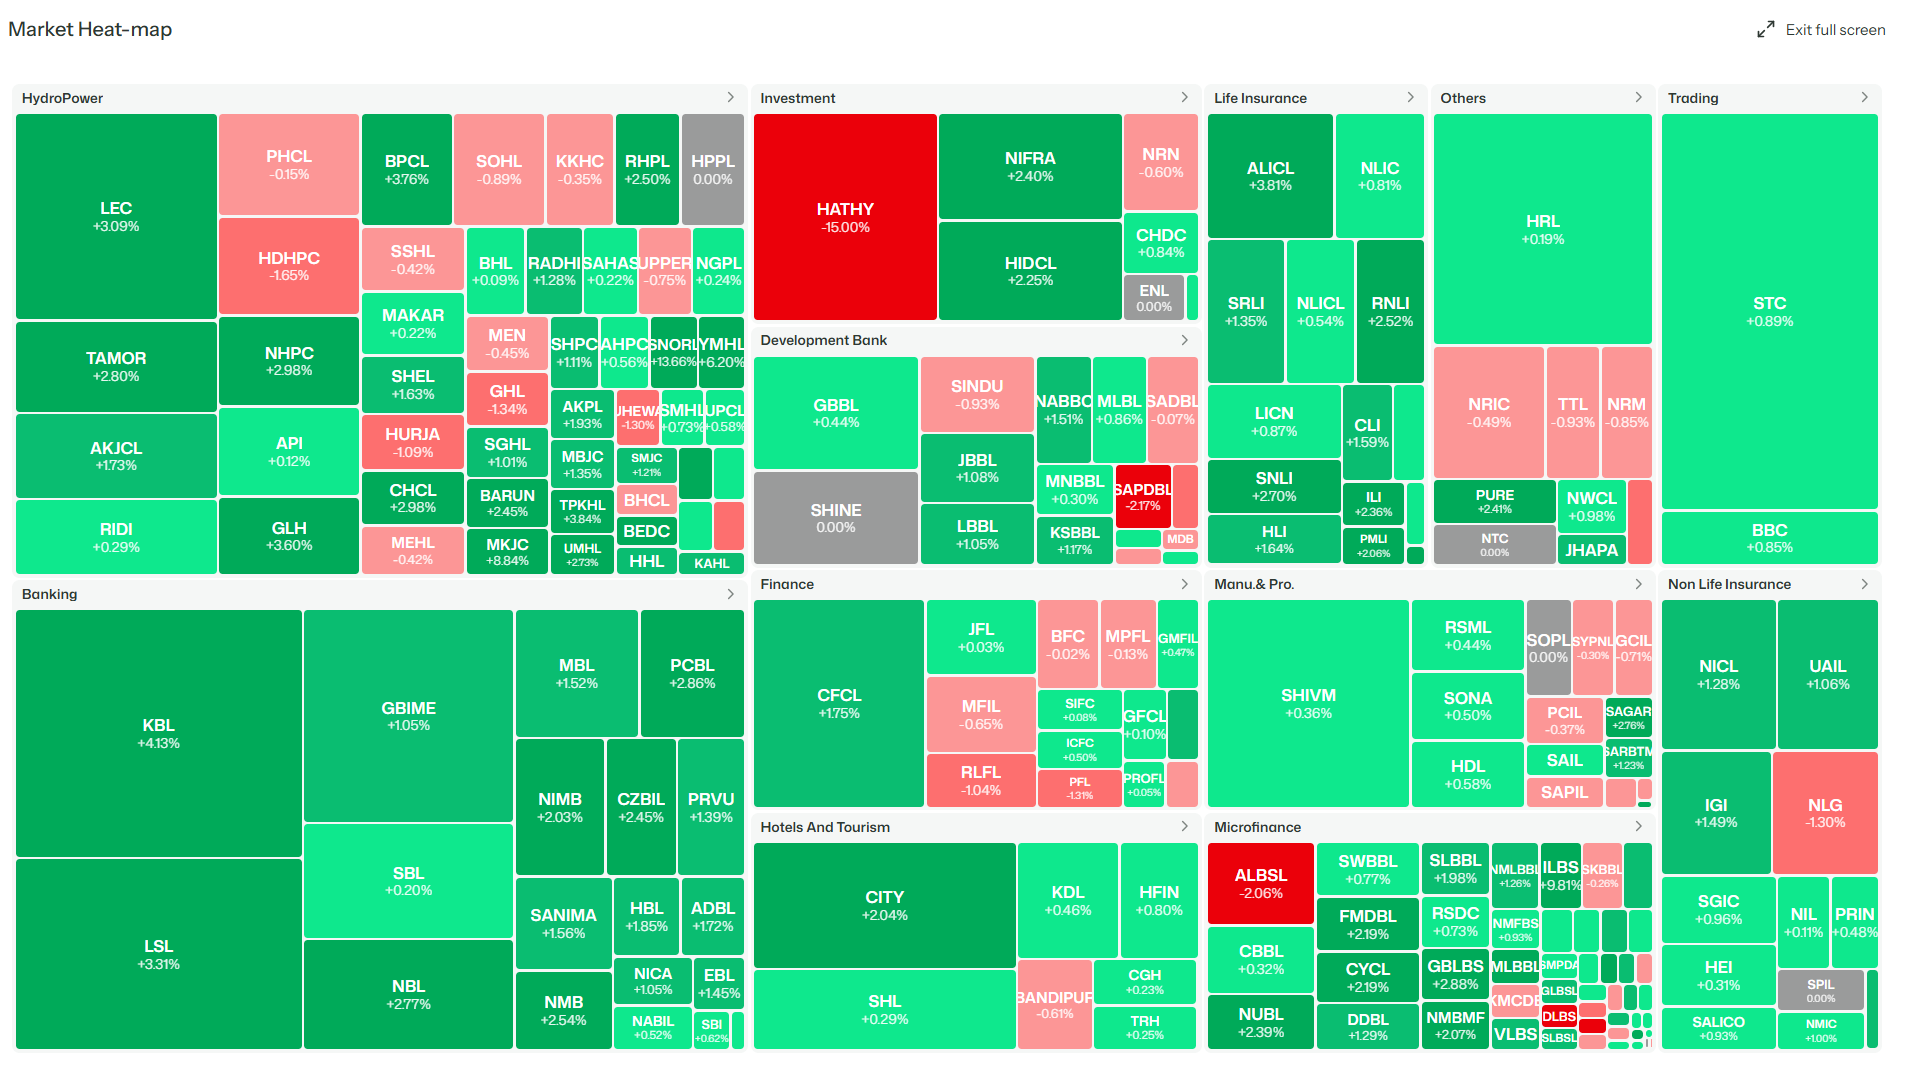
Eleven up, two down. Float (182.46, +1.03%) is a broad index, not a sub-index.
Life Insurance at +1.52% is on a two-day run: +1.08% yesterday, +1.52% today with ALICL +3.81%, SNLI +2.70%, RNLI +2.52%, HLI +1.64%, CLI +1.59%, SRLI +1.35%. That is the second-broadest sector move after Banking.
Investment at +0.10% is HATHY's limit-down being offset by NIFRA +2.40%, HIDCL +2.25% and CHDC +0.84%. Without HATHY the sector would be among the leaders.
Market Breadth
Metric | Count |
|---|---|
Advancers | 196 |
Decliners | 74 |
Unchanged | 12 |
Live universe | 282 |
A/D ratio | 2.65 |
A/D series (last eight captured sessions): 0.39 → 0.34 → 7.65 → [gap] → 22.08 → 0.19 → 2.08 → 2.65
Two consecutive above-parity readings, both in normal territory. After a record 22.08 and a near-record 0.19 in consecutive sessions, 2.08 followed by 2.65 is the first pair of unremarkable breadth prints in over a week and rising breadth on rising turnover with the index clearing resistance is the healthiest configuration this report has recorded.
The standing caution still applies: every above-parity streak in this coverage has eventually reverted, and the record four-session run ended in a slide that erased it. But 2.65 is not an exhaustion reading. 74 decliners on a day the index gained 0.87% is a normal market.
Winners & Losers
Top Gainers
Stock | Sector | LTP | % |
|---|---|---|---|
SNORL | HydroPower | 1,057.00 | +13.66% |
ILBS | Microfinance | 1,065.00 | +9.81% |
MKJC | HydroPower | 320.00 | +8.84% |
YMHL | HydroPower | 589.40 | +6.20% |
BNT | Manu. & Pro. | 12,450.00 | +5.06% |
AHL | HydroPower | 395.00 | +4.47% |
IHL | HydroPower | 338.10 | +4.26% |
KBL | Banking | 227.00 | +4.13% |
TPKHL | HydroPower | 524.00 | +3.84% |
ALICL | Life Insurance | 432.90 | +3.81% |
SNORL is Snow Rivers Limited, and this is a dividend move. It proposed a 10.5263% dividend and called its 5th AGM on 15 September; the stock rose 2.79% on 17 September and +13.66% today. That makes the cash-dividend thread 5 for 5.
KBL is the only gainer backed by the heaviest money on the exchange, top of both activity tables at Rs 32.14 crore and 14.26 lakh shares. Kumari Bank proposed a 2.1053% cash dividend on 16 September, which is small enough that the dividend alone does not explain a 4.13% move on this volume. Read KBL as the lead name in a sector rotation rather than a dividend trade.
IHL rose 4.26% on a second consecutive session (+3.66% on 9 September, then again today), it is plausibly Ingwa Hydropower, which resumed full generation at its 9.7 MW Upper Ingwa Khola project after repairing flood damage.
Top Losers
Stock | Sector | LTP | % |
|---|---|---|---|
HATHY | Investment | 499.80 | −15.00% |
DLBS | Microfinance | 1,184.00 | −5.13% |
MATRI | Microfinance | 739.00 | −2.64% |
BGWT | HydroPower | 481.00 | −2.24% |
SAPDBL | Development Bank | 626.00 | −2.17% |
ALBSL | Microfinance | 1,190.00 | −2.06% |
MKCL | Others | 879.00 | −1.79% |
HDHPC | HydroPower | 220.50 | −1.65% |
MLBS | Microfinance | 1,020.00 | −1.46% |
SIPD | HydroPower | 580.00 | −1.36% |
Only 74 names fell, and outside HATHY and DLBS nothing lost more than 2.64%.
HATHY's limit-down is the largest single-name decline of the coverage larger than PURE's −13.33%, larger than the ENL, JFL and SINDU limit-downs at −14.99%. The arc: +5.56% on 11 September on the Rs 40 crore capital-deployment announcement, −2.97% on 17 September, −15.00% today. 609.00 → 499.80 is −18.0% in five sessions. No news has surfaced to explain it and that absence is itself worth flagging in a name that was moving on a corporate announcement a week ago.
DLBS −5.13% after +12.43% yesterday, the one-session churn pattern, still alive in microfinance. Five of the ten losers are microfinance, against a sector index of +0.75%. Microfinance dispersion is now in its second week.
HDHPC −1.65% completes the fade of Tuesday's leader which took Rs 37.96 crore and 7.0% of the tape on 16 September at +5.31%.
Turnover & Volume Leaders
Most Active by Turnover
Stock | LTP | % | Turnover |
|---|---|---|---|
KBL | 227.00 | +4.13% | Rs 32.14 Cr |
LSL | 246.40 | +3.31% | Rs 27.16 Cr |
GBIME | 260.90 | +1.05% | Rs 23.20 Cr |
LEC | 259.90 | +3.09% | Rs 22.80 Cr |
SBL | 447.90 | +0.20% | Rs 21.78 Cr |
TAMOR | 547.90 | +2.80% | Rs 21.07 Cr |
SHIVM | 688.00 | +0.36% | Rs 17.86 Cr |
BPCL | 698.00 | +3.76% | Rs 14.97 Cr |
SOHL | 665.00 | −0.89% | Rs 14.49 Cr |
RSML | 2,757.00 | +0.44% | Rs 14.15 Cr |
Most Active by Volume
KBL (14.26 L, +4.13%), LSL (11.07 L, +3.31%), GBIME (8.95 L, +1.05%), LEC (8.79 L, +3.09%), SBL (4.85 L, +0.20%), NBL (4.69 L, +2.77%), TAMOR (3.86 L, +2.80%), AKJCL (3.69 L, +1.73%), RIDI (3.23 L, +0.29%), MBL (3.19 L, +1.52%)
Six of the ten most-traded names are banks. In twenty-six sessions of coverage, banks have appeared in these tables a handful of times and never more than four at once. The turnover top five is four banks and LEC.
Concentration is the lowest of the coverage. The largest single name, KBL, is 4.8% of turnover against LEC at 11.4% on 10 September and HDHPC at 7.0% on 16 September. The top five are roughly 19% of a Rs 6.75 arab pie. Broad money in liquid names is the opposite of what this market has been doing all month.
SBL is the dividend test result. It proposed 20% on 17 September, closed +3.71% that day, and today closed +0.20% while still fourth by turnover at Rs 21.78 crore. It held the gain without extending, the same pattern as GBIME (+4.13% then +0.04%) and GBBL. Cash dividends remain 5 for 5 on the announcement move and 0 for 5 on building on it.
RSML broke its three-day decline at +0.44%, and SOHL was the only red name in the turnover table at −0.89%.
BPCL is new at +3.76% on Rs 14.97 crore worth watching next session.
Signal Scorecard
Prior call | Status | What happened |
|---|---|---|
"The 2,629–2,633 zone, second attempt 4.64 points away. Clearing it on a quieter attempt would be more meaningful than Tuesday's spike" | CLEARED | Closed 2,647.22, comfortably through. It came on bank buying with breadth at 2.65 rather than a 22.08 blow-off. The coverage drawdown is now −0.11%. |
"Does SBL hold its dividend gain for a second session?" | HELD, DIDN'T EXTEND | +0.20%, still fourth by turnover. Cash dividends: 5 for 5 on the move, 0 for 5 on building on it. The tax has not yet changed this. |
"Turnover's sustainable level toward Rs 4 arab as the tax bites, or above Rs 5 arab?" | ABOVE, AND RISING | Rs 6.75 arab, up Rs 1.25 billion. Volume 2.13 crore is the coverage high. Four consecutive sessions above Rs 5 arab. The deposit surplus is overwhelming the tax. |
"RSML on day four, downward" | BROKE | +0.44% to 2,757.00, ending three consecutive declines. Still tenth by turnover. |
"Block data, unresolved" | STILL UNRESOLVED | No Bulk Transaction capture again this session. The question of whether large holders are exiting into the tax change carries forward untested for a second day. |
"The Ashwin AGM cluster, watch the proposals still to come" | SNORL DELIVERED | Snow Rivers +13.66%, the day's best, three sessions after its 10.5263% proposal. Sarvottam Paints proposed 10% and called its 5th AGM today; Global IME Balanced Fund-1 set book closure for a 12% cash dividend. |
"Do large caps keep leading?" | YES, EMPHATICALLY | Sensitive ~+1.15%, Sensitive Float ~+1.21% against NEPSE +0.87%, with six banks in the volume table. |
"Capital allocation 0 for 7" | WORSE — HATHY LIMIT-DOWN | −15.00% to 499.80, −18.0% from its 11 September announcement-day high. The largest single-name decline of the coverage, unexplained. |
Top Stories
1. Rs 215.05 billion in one month, the liquidity surplus finally has a source
Remittance inflows rose 21.2% to Rs 215.05 billion in the first month of FY 2026/27, covering 17 July to 16 August, per Nepal Rastra Bank. Net secondary income increased to Rs 229.98 billion from Rs 193.85 billion.
Why this matters more than anything else in today's report. For a week this coverage has identified the liquidity surplus as the actual driver of this rally, repo at 4.25%, credit-to-deposit at roughly 74% against a 90% ceiling, one-year FD at ~4.55%, savings at 2.9%, and average bank rates falling again in Ashwin. What was missing was the source of the deposits. This is it.
Put Rs 215.05 billion in context. It is more than the entire Rs 166.50 billion margin-lending book outstanding against share collateral arriving in thirty days. It is roughly 32 times today's record turnover. Remittance lands in bank deposits, banks cannot lend it out fast enough to move the CD ratio, deposit rates fall, and the money looks for a return. NRB's own data showing real estate transactions up 4.74% is the same money. Today's Rs 6.75 arab of turnover and 2.13 crore of volume is the same money.
But read the deceleration carefully, because it is the single best forward indicator in this report. Growth of 21.2% is down from 29.9% in the same period a year earlier. In US dollar terms the increase is only 10.2%, against 25% a year ago meaning a substantial part of the rupee gain is currency, not volume. And the labour pipeline is thinning: 42,693 Nepalis received new foreign employment approvals, down from 44,466, with the shortfall covered by re-entry approvals rising to 27,748 from 23,644. Fewer new workers going out, more returning workers going back.
The chain runs: remittance growth → deposit growth → low rates → equity inflows. The first link is decelerating. That is the thing to watch, not the index.
2. The trade deficit widened 24.9% in the same month
Nepal's merchandise trade deficit increased 24.9% to Rs 148.74 billion in the first month of the current fiscal year.
Why it matters: remittance of Rs 215.05 billion against a monthly merchandise deficit of Rs 148.74 billion is the arithmetic that holds the external account together. Remittance is growing at 21.2%; the deficit is growing at 24.9%. If that gap persists, the buffer narrows.
It also compounds three things already in this report. India has approved up to 654 MW of power supply to Nepal for 18 hours daily import volumes that reverse a roughly NPR 19.97 billion net electricity trade surplus. Rasuwagadhi remains closed with customs revenue there, around NPR 13.64 billion annually, impaired. And government revenue is running at 11.59% of annual target after two months against a reconstruction bill estimated near NPR 560 billion.
Every one of those pressures points the same direction, and none of them is in the price. The index is flat over the coverage while the external and fiscal position has deteriorated measurably.
3. Banks take the tape and it is not a dividend trade
Banking rose 1.59%, the best of thirteen sub-indices, with twelve of fourteen visible constituents up and six banks in the volume top ten.
Bank | Close | % | Turnover |
|---|---|---|---|
Kumari Bank (KBL) | 227.00 | +4.13% | Rs 32.14 Cr |
Laxmi Sunrise (LSL) | 246.40 | +3.31% | Rs 27.16 Cr |
Global IME (GBIME) | 260.90 | +1.05% | Rs 23.20 Cr |
Siddhartha (SBL) | 447.90 | +0.20% | Rs 21.78 Cr |
Nepal Bank (NBL) | 296.50 | +2.77% | — |
Machhapuchchhre (MBL) | 260.80 | +1.52% | — |
Why it matters, and why it is different. Every rally in this coverage has been carried by something unreliable hydropower thin prints running 10% on a handful of trades, a single name taking 11.4% of turnover, or a one-day headline. Today the money went into the most liquid, most heavily capitalised names on the exchange, and no single stock took more than 4.8% of turnover.
It is also not simply the dividend trade. KBL proposed only 2.1053% cash on 16 September too small to explain 4.13% on 14.26 lakh shares. SBL, which proposed 20% yesterday, closed +0.20%. The dividend names are not the ones leading; the sector is moving as a sector.
The plausible mechanism is the one from story one. Banks are the direct beneficiaries of a deposit surge they cannot lend out — and at a CD ratio near 74% with rates falling, the deposit franchise is growing while the loan book is not. That is margin-compressing in the short run and balance-sheet-expanding in the long run. Whether the market is pricing that or simply rotating into liquidity is the question a second session answers.
4. Hathway limit-down: −18% in five sessions, no explanation
HATHY closed limit-down at −15.00% to 499.80, the largest single-name decline recorded in this coverage.
The sequence: on 11 September the company announced it would invest up to Rs 40 crore in a sugar mill and a hydropower project, and the stock rose +5.56% to 609.00. That was logged here as the first capital-allocation announcement in seven attempts to actually move a price. It then fell −2.97% on 17 September and −15.00% today. 609.00 → 499.80 is −18.0%.
No public explanation has surfaced in either ShareSansar's or Nepalytix's feeds. That absence matters. In a market where the ENL collapse preceded its shareholder-sale disclosure by two sessions, an unexplained limit-down in a name that was recently making acquisition announcements is worth treating as information that has not yet been published rather than as noise. Watch for a disclosure, a rating action, or a shareholder filing.
The capital-allocation thread now reads 0 for 8, and worse than 0 — the one announcement that worked has fully reversed and then some.
5. Dividend season: three more, and the pattern holds
Sarvottam Paints called its 5th AGM and proposed a 10% dividend. Global IME Balanced Fund-1 set book closure for a 12% cash dividend. And Snow Rivers, which proposed 10.5263% on 15 September, was the day's biggest gainer at +13.66%.
The running scoreboard:
Announcement | Reaction | Held? |
|---|---|---|
SNORL 10.5263% | +13.66% (3 sessions later) | TBD |
SBL 20% | +3.71% | +0.20% day two |
GBBL 20% | +2.45% | Faded |
GBIME 10% (6% cash) | +4.13% | +0.04% day two |
H8020 15% cash | Record unit volume | — |
MBL 6% | +0.80% | — |
KDL 8.9474% (8.5% bonus) | −14.28% | — |
Cash dividends: 5 for 5 on producing a move. 0 for 5 on extending it. Bonus-dominant: 0 for 1.
The new tax has not changed this yet. The incentive to hold past 365 days, 3.5% versus 5% advance tax, collected at source should in theory make announcement-day gains stickier. Two sessions in, they are not. Reliance Spinning's 30% cash book closure is set, GBIME and KDL are both Ashwin 16, Nabil Investment Banking is Ashwin 20, Reliance Spinning is Ashoj 22. That cluster is the real test.
6. National Life to cover Nepal Bank employees
Nepal Bank employees will receive life insurance coverage from National Life.
Small in isolation, but it lands in the week Life Insurance became the second-best sector two sessions running +1.08% then +1.52%, with ALICL +3.81%, SNLI +2.70% and RNLI +2.52%. Group corporate mandates are the growth channel for life insurers in a market where retail penetration is low, and this is the second life-insurance-positive item in three sessions after Life Insurance separated from Non-Life for the first time in a fortnight.
Corporate Actions & Events
Company | Action | Detail |
|---|---|---|
Sarvottam Paints | Dividend | 10% proposed, 5th AGM called |
Global IME Balanced Fund-1 | Book closure | 12% cash dividend |
Snow Rivers (SNORL) | Dividend | 10.5263% · 5th AGM, stock +13.66% today |
Siddhartha Bank (SBL) | Dividend | 20% proposed, +0.20% day two |
Kumari Bank (KBL) | Dividend | 2.1053% cash, +4.13%, top of both tables |
Bikash Hydropower | Dividend | 10.5263% proposed |
ICRA Nepal | Dividend | 62.50% proposed, 14th AGM |
Reliance Spinning Mills | Dividend | 30% cash book closure set, AGM Ashoj 22 |
Citizens Bank (CZBIL) | Dividend | 4% proposed |
Nabil Investment Banking | Dividend | 10% bonus + 11.05% cash, AGM Ashwin 20 |
Global IME Bank (GBIME) | Dividend | 10% (4% bonus + 6% cash), AGM Ashwin 16 |
Kalinchowk Darshan (KDL) | Dividend + sales | 8.9474% · AGM Ashwin 16, major shareholders selling |
Kamana Sewa (KSBBL) | Approved | 15% cash approved at 20th AGM |
Nepal Bank / National Life | Business | Employee life insurance coverage mandate |
Upper Hewakhola (UHEWA) | Shareholder sales | Two holders, 134,601 shares |
Emerging Nepal (ENL) | Shareholder sales | 7 holders, 913,099 shares |
Trishuli Jal Vidyut (TVCL) | Rating | Rs 8.2 bn loans on NEGATIVE WATCH |
Sagarmatha Jalabidhyut | Rating | BBB-, Watch with Negative Implication |
Himalayan Reinsurance (HRL) | Board | Chair still vacant |
Shikhar Power Development | Lock-in expiry | 1.11 lakh units , Ashwin 2, 2083 |
— | Tax | Advance tax on securities gains: 5% ≤365 days, 3.5% >365 days, at source |
What to Watch
1. 2,650.08 — 2.86 points away. Clearing the coverage starting level would put the index into territory this report has no data on. There is no tested resistance above it within the dataset. The nearest historical reference from the carried notes is the 2,629–2,633 zone that broke on 18 August, now cleared, and nothing above.
2. Does the bank rotation survive a second session? Six banks in the volume top ten and four in the turnover top five is unprecedented here. Sixteen of seventeen rotations in this coverage died on day three. Banking is on day one. KBL, LSL and NBL are the names; watch whether the sector index holds above +0.5% rather than whether individual names extend.
3. Remittance deceleration. 21.2% growth against 29.9% a year ago, and only 10.2% in dollars against 25%. New labour approvals fell to 42,693 from 44,466. This is the source of the deposit surplus funding the rally, and its growth rate is halving in dollar terms. Next month's NRB release is more consequential for this market than any index level.
4. Turnover at Rs 6.75 arab against the new tax. Four consecutive sessions above Rs 5 arab, volume at a coverage high, and the tax has been live for two full sessions with no visible effect. If turnover holds above Rs 6 arab next week, the 5%/3.5% differential is too small to matter and the liquidity thesis wins outright.
5. HATHY: the unexplained limit-down. −18.0% in five sessions with no published cause, in a name that was announcing Rs 40 crore of acquisitions a week ago. Watch for a SEBON disclosure, a rating action, or a shareholder filing. The ENL precedent price collapsing two sessions before the disclosure appeared argues for treating this as unpublished information.
6. Block data, two sessions missing. No Bulk Transaction capture on 17 or 18 September. The open question from 16 September whether large holders are distributing into the tax change — remains untested. On that session, two of the three largest blocks came with falling prices. With turnover now at Rs 6.75 arab, the block tape matters more, not less.
7. The trade deficit and the fiscal file. Deficit up 24.9% to Rs 148.74 billion monthly; revenue at 11.59% of target; reconstruction near NPR 560 billion; 654 MW of power imports approved; Rasuwagadhi still shut. None of this is priced, and the index is now flat over a coverage in which all of it happened.
Disclaimer
This report has been prepared by Nepalytix for informational and educational purposes only and does not constitute investment advice, an offer, or a solicitation to buy or sell any securities.
The information contained in this report is based on sources believed to be reliable; however, Nepalytix does not guarantee its accuracy, completeness, or timeliness. Opinions, estimates, and projections expressed herein are those of the authors as of the date of publication and are subject to change without notice.
Investing in securities involves risks, including the possible loss of principal. Past performance is not indicative of future results. Readers are advised to conduct their own independent research and consult with a qualified financial advisor before making any investment decisions.
Nepalytix and its contributors may hold positions in the securities discussed in this report at the time of publication or thereafter.
Neither Nepalytix nor any of its affiliates accept any liability for any loss arising from the use of this report or its contents.