NEPSE Falls 16.47 Points Below 2630 Again
NEPSE fell 0.62% to 2,613.33 while market breadth collapsed to 0.22. HATHY fell another 10.58%, taking its 13-session decline to 33.5%.
Markets Today
The 30-Second Read
NEPSE closed 2,613.33, down 16.47 (−0.62%) on the first session after the three-day Indra Jatra closure. Back below the 2,629–2,633 zone, its fifth role reversal in eight sessions.
Breadth 0.22, 49 advancers against 223 decliners. The fourth-worst reading of the coverage.
The gainer table is the weakest ever recorded here. Top gainer MANDU +5.38%; the second-best was +1.27%. Only one name on the entire board rose more than 1.3%.
NRB will absorb another Rs 30 arba from banks to manage excess liquidity. That is on top of the Rs 85 billion already being withdrawn, a direct drain on the deposit surplus this report identified as the rally's engine.
Gold fell Rs 5,000 per tola and silver Rs 145, the largest single-day bullion move of the coverage.
HATHY fell 10.58% to 405.00, a sixth consecutive decline. It is now down 33.5% from its 11 September high and was top by volume and third by turnover at Rs 19.99 crore. Still no disclosure.
ENL fell 9.92% to 496.00, the name carrying a 913,099-share overhang across seven holders.
Machhapuchchhre Bank led a Rs 9 arba consortium loan for the 63 MW Chhujung Khola project, fresh bank exposure to hydro on the day another project went offline from flood damage.
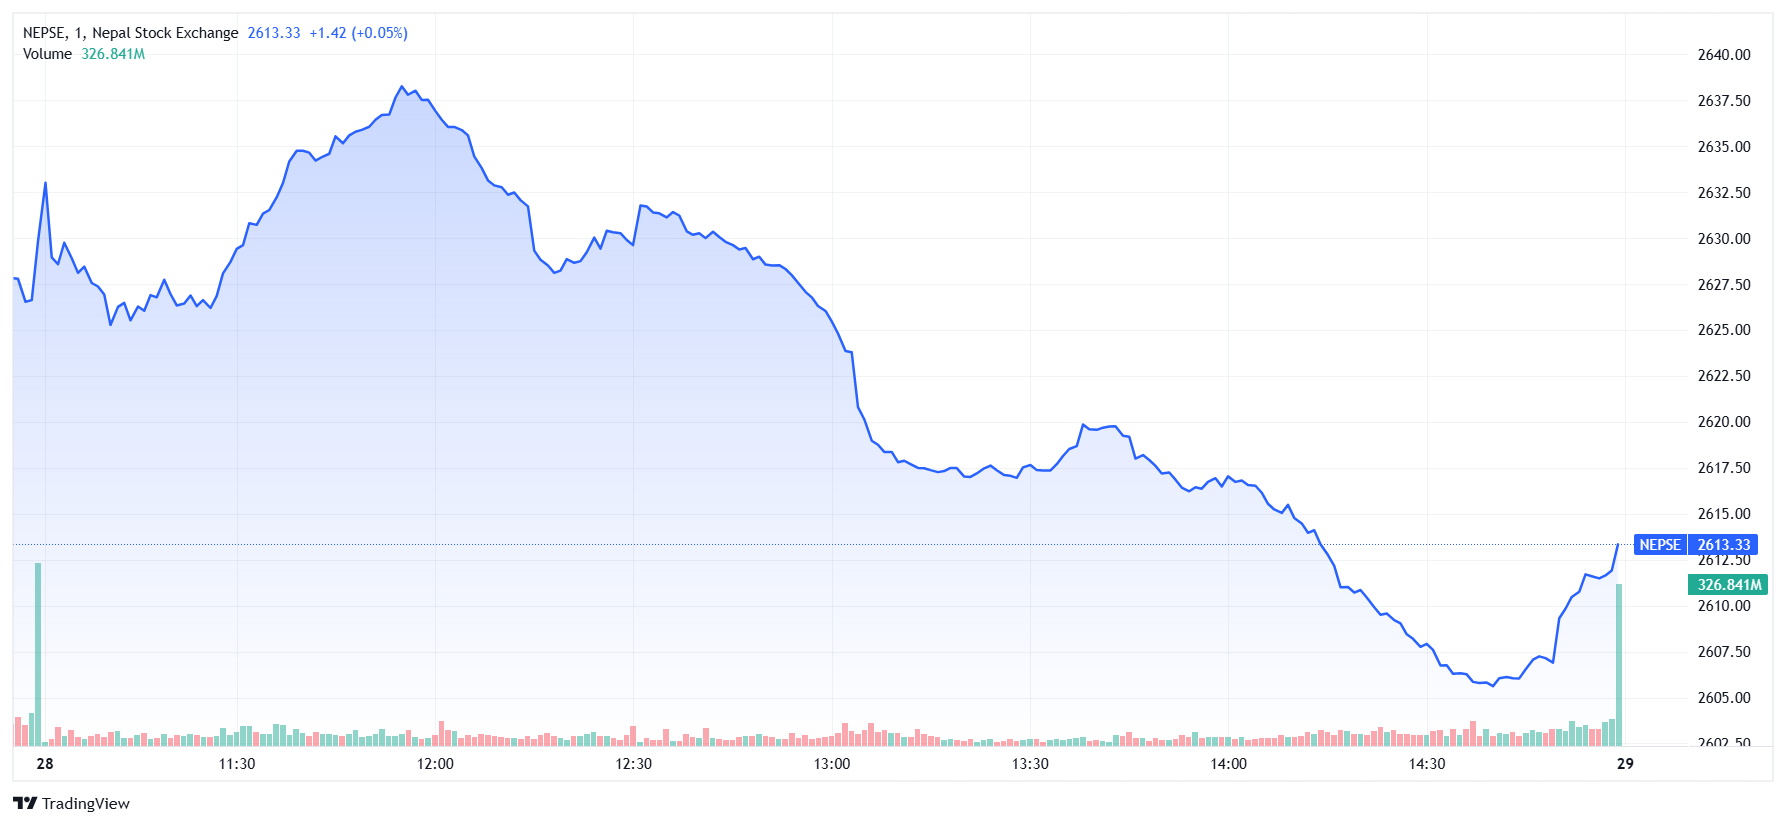
The market reopened after three days closed and did what this report warned a gap would do: it moved decisively, and downward.
NEPSE closed 2,613.33, down 16.47 points (−0.62%), on Rs 5.39 arab, 1.32 crore units and 58,500 transactions across 357 scrips, another coverage high for scrip count. Advancers 49, decliners 223, unchanged 10 an A/D of 0.22.
Only Trading closed green, at +0.23%. Eleven of twelve captured sub-indices fell, led down by Non-Life Insurance −1.20%, Investment −1.16% and HydroPower −1.03%.
The gainer table is the weakest in twenty-nine captured sessions. MANDU at +5.38% is the only name above 1.3%; second place is RSML at +1.27% and the tenth-best gainer managed +0.84%. In a market that routinely produces limit-ups, a board where 49 names rose and almost none rose meaningfully is a market with no bid, not one with sellers.
Look at the ticket size. Turnover held roughly flat at Rs 5.39 arab against Rs 5.45 arab, but volume fell 24% to 1.32 crore while transactions rose 13% to 58,500. Average value per trade fell from about Rs 105,400 to roughly Rs 92,100. More trades, smaller each, less stock changing hands. That is retail churn absorbing supply, not institutions repositioning.
Large caps were the only shelter. Sensitive fell 0.28% against NEPSE's 0.62% and Float's 0.61%. Banking closed −0.19%, second-best sector, with PCBL +1.17%, CZBIL +0.75%, NBL +0.68%, LSL +0.36% and SBL +0.20% against NIMB −1.03% and HBL −0.66%.
Two single names did most of the damage. HATHY −10.58% and ENL −9.92% are both Investment-sector constituents, and together they account for that sector's −1.16%. HATHY was the most-traded stock in the market by volume.
Index Snapshot
Index | Close | % |
|---|---|---|
NEPSE | 2,613.33 | −0.62% |
Sensitive | 467.67 | −0.28% |
Float | 180.07 | −0.61% |
Turnover Rs 5.39 arab
Volume 1.32 crore units
Transactions 58,500
Scrips traded 357 (coverage high)
Sectoral Indices Performance
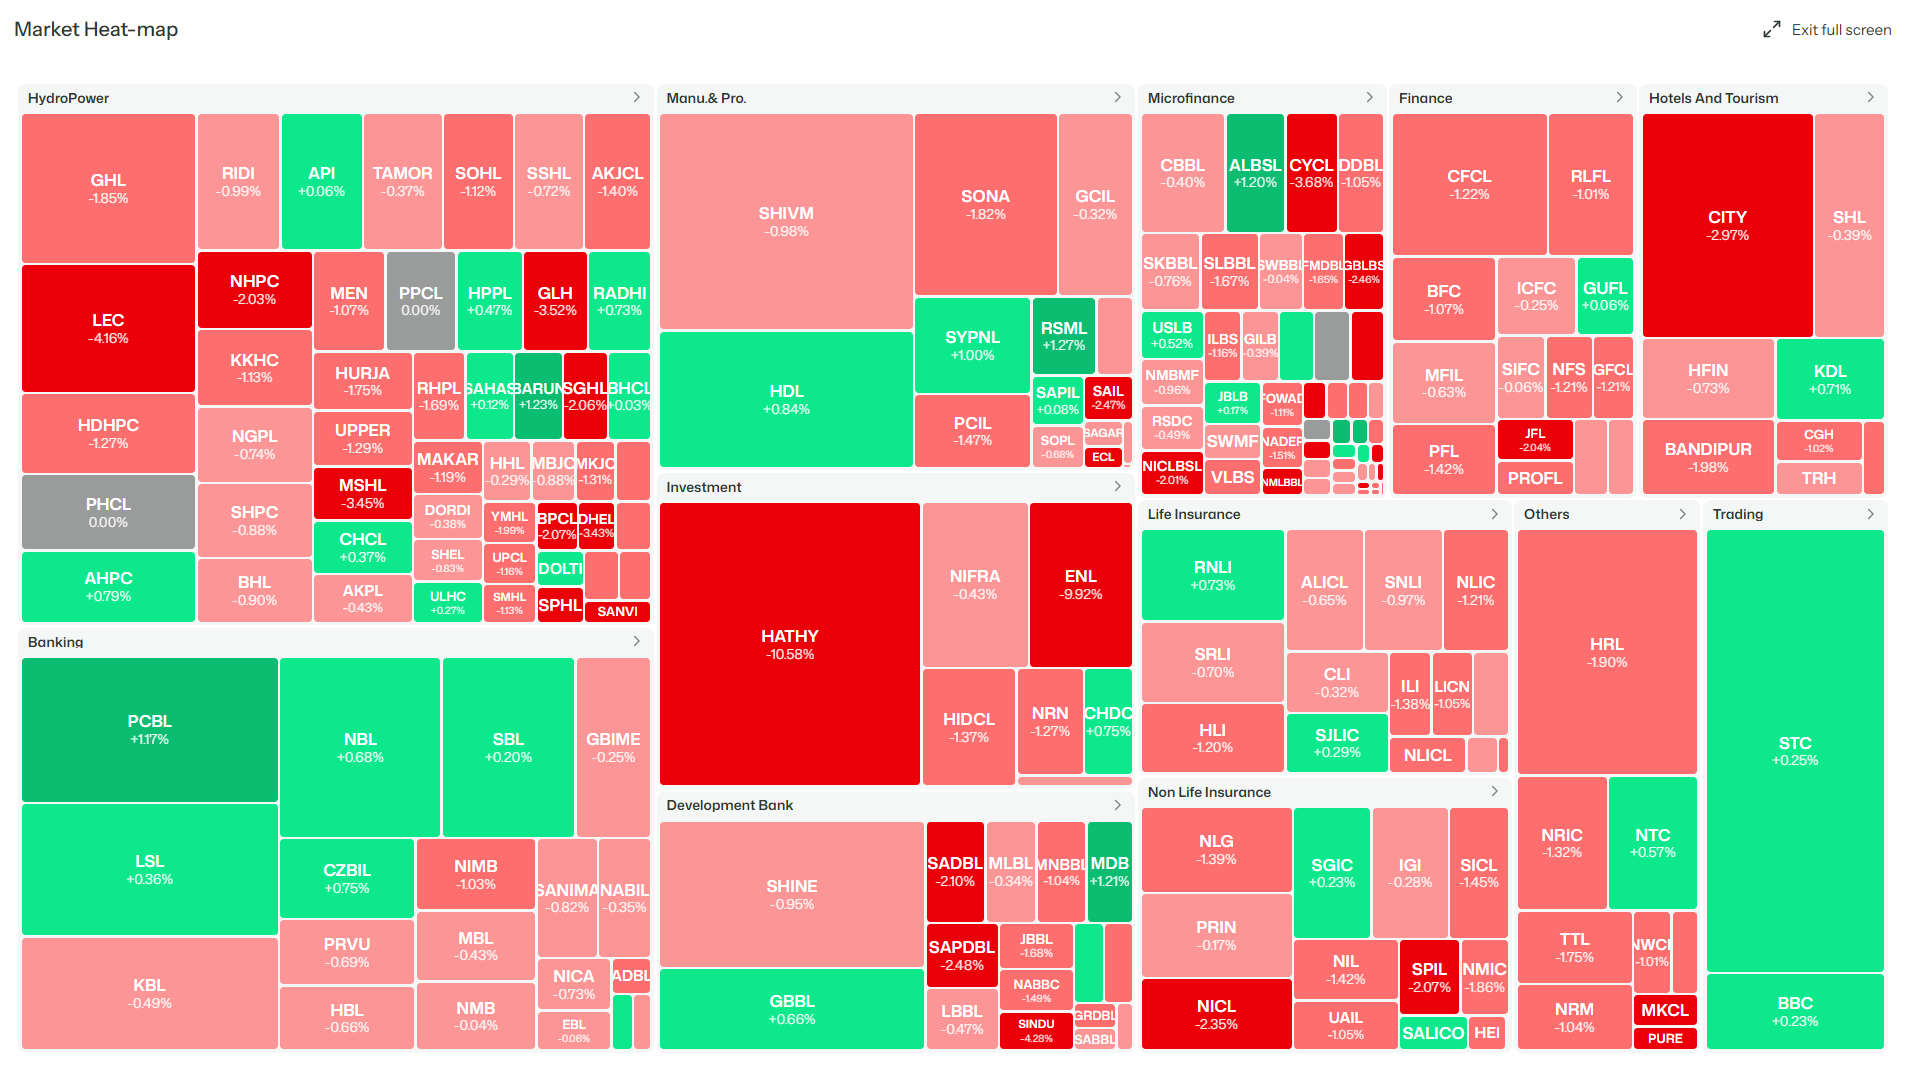
One green sector out of twelve captured. Float (180.07, −0.61%) is a broad index, not a sub-index. Others is negative on HRL −1.90%, TTL −1.75%, NRIC −1.32% and NRM −1.04%.
Non-Life's −1.20% comes on the day United Ajod's bonus shares listed — NICL −2.35%, SPIL −2.07%, NMIC −1.86%, NLG −1.39%, NIL −1.42%, SICL −1.45%, UAIL −1.05%.
Investment is a two-stock wreck. HATHY −10.58% and ENL −9.92% against NIFRA −0.43%, HIDCL −1.37% and CHDC +0.75%.
Market Breadth
Metric | Count |
|---|---|
Advancers | 49 |
Decliners | 223 |
Unchanged | 10 |
Live universe | 282 |
A/D ratio | 0.22 |
A/D series (last eight captured sessions): 2.08 → 2.65 → [gap] → 0.09 → 1.85 → [3-day closure] → 0.22
Fourth-worst reading of the coverage, behind 0.08 (31 Aug), 0.09 (23 Sep) and 0.19 (16 Sep). Three of those four have come in the last two weeks.
Scrips traded at 357 is another record, against a live universe of 282 — a 75-instrument gap, again the widest recorded. Combined with 58,500 transactions, the widest scrip participation of the coverage delivered the fourth-worst breadth. Everything traded; almost nothing rose.
Winners & Losers
Top Gainers
Stock | Sector | LTP | % |
|---|---|---|---|
MANDU | HydroPower | 780.00 | +5.38% |
RSML | Manu. & Pro. | 2,789.00 | +1.27% |
BARUN | HydroPower | 330.00 | +1.23% |
MDB | Development Bank | 566.80 | +1.21% |
ALBSL | Microfinance | 1,188.50 | +1.20% |
PCBL | Banking | 260.00 | +1.17% |
HLBSL | Microfinance | 878.90 | +1.14% |
MATRI | Microfinance | 735.00 | +1.09% |
SYPNL | Manu. & Pro. | 1,333.00 | +1.00% |
HDL | Manu. & Pro. | 1,323.00 | +0.84% |
The gap between first and second place 5.38% to 1.27% is the largest in the coverage, and the second-place figure is the lowest. For comparison, the tenth-best gainer on 15 September was up 5.32%; today it is up 0.84%.
Three of the ten have real money behind them. PCBL is third by volume at 4.18 lakh shares and seventh by turnover; HDL tops the turnover table at Rs 35.82 crore; RSML is sixth at Rs 11.17 crore.
MANDU's +5.38% appears in neither activity table, the usual thin-print caution applies, and it is the same name whose chairman was re-appointed on 10 September.
Top Losers
Stock | Sector | LTP | % |
|---|---|---|---|
HATHY | Investment | 405.00 | −10.58% |
ENL | Investment | 496.00 | −9.92% |
DLBS | Microfinance | 1,149.00 | −4.66% |
AHL | HydroPower | 385.00 | −4.40% |
SINDU | Development Bank | 400.00 | −4.28% |
LEC | HydroPower | 244.20 | −4.16% |
TVCL | HydroPower | 293.00 | −3.93% |
CYCL | Microfinance | 1,570.00 | −3.68% |
GLH | HydroPower | 269.00 | −3.52% |
MSHL | HydroPower | 531.00 | −3.45% |
HATHY's sixth consecutive decline takes the collapse to −33.5% from 609.00 on 11 September, the session it rose 5.56% on announcing up to Rs 40 crore of investment into a sugar mill and hydropower. Sequence: +5.56% → −2.97% → −15.00% → −4.09% → −3.43% → −10.58%. Nineteen calendar days, thirteen sessions, no SEBON filing, no rating action, no shareholder disclosure.
ENL's −9.92% is the name where seven holders filed to sell 913,099 shares over three months, and where the price collapsed two sessions before the disclosure was published. From 620.00 on 10 September to 496.00 is −20.0%.
DLBS fell 4.66%, a third consecutive decline from its 1,341.90 limit-up on 23 September — −14.4% in three sessions. This report flagged it as a thin print on the day it hit the circuit.
TVCL −3.93% to 293.00 — the name carrying Rs 8.2 billion of loans on ICRA negative watch. It has given back the entire two-session bounce.
LEC −4.16% continues fading from the name that took 11.4% of all turnover on 10 September.
Turnover & Volume Leaders
Most Active by Turnover
Stock | LTP | % | Turnover |
|---|---|---|---|
HDL | 1,323.00 | +0.84% | Rs 35.82 Cr |
SHIVM | 695.10 | −0.98% | Rs 29.79 Cr |
HATHY | 405.00 | −10.58% | Rs 19.99 Cr |
SBL | 457.70 | +0.20% | Rs 12.38 Cr |
SYPNL | 1,333.00 | +1.00% | Rs 11.82 Cr |
RSML | 2,789.00 | +1.27% | Rs 11.17 Cr |
PCBL | 260.00 | +1.17% | Rs 10.91 Cr |
LSL | 250.90 | +0.36% | Rs 9.63 Cr |
NBL | 294.00 | +0.68% | Rs 9.54 Cr |
SHINE | 428.90 | −0.95% | — |
Most Active by Volume
HATHY (4.80 L, −10.58%), SHIVM (4.24 L, −0.98%), PCBL (4.18 L, +1.17%), LSL (3.82 L, +0.36%), GHL (3.69 L, −1.85%), KBL (3.27 L, −0.49%), NBL (3.24 L, +0.68%), LEC (3.15 L, −4.16%), SBL (2.70 L, +0.20%), HDL (+0.84%)
HDL topped turnover for a second consecutive session and has been top-three for three sessions running Rs 20.54 Cr, Rs 35.17 Cr, Rs 35.82 Cr while rising 1,278.30 → 1,312.00 → 1,323.00. It is the closest thing to sustained leadership on the board, and Manufacturing was the third-best sector at −0.30%.
SHIVM held second by turnover for a third session but closed −0.98%, breaking a two-session gain.
HATHY is the number that matters. Most-traded by volume, third by turnover at Rs 19.99 crore, and down 10.58%. Two consecutive sessions of heavy volume against a falling price, after eleven sessions of quiet decline. On 24 September it entered both tables for the first time at Rs 11.93 crore; today that is Rs 19.99 crore. Size is leaving in a hurry and nothing has been published.
Five banks in the volume table: PCBL, LSL, KBL, NBL, SBL four of them green. Banking was the only meaningful pocket of stability.
Signal Scorecard
Prior call | Status | What happened |
|---|---|---|
"Monday's open carries three days of news, size for a gap, not a drift" | CORRECT | −16.47 with 223 decliners and the weakest gainer table of the coverage. |
"Does microfinance finally price the NPL data?" | PARTIALLY | Microfinance −0.82% with DLBS −4.66% and CYCL −3.68%, but ALBSL, HLBSL and MATRI all rose ~1.1%. A soft reaction to a Rs 50.82 bn NPL disclosure earnings and asset-quality news now 0 for 8 on producing a proportionate move. |
"HATHY — the three-day close is exactly the window in which a disclosure would land" | NO DISCLOSURE, WORST DAY YET | −10.58% to 405.00, −33.5% from the high, top by volume, Rs 19.99 Cr turnover. Thirteen sessions, nothing published. |
"The 2,629–2,633 zone, from inside" | LOST AGAIN | Closed 2,613.33, below the band. Fifth role reversal in eight sessions. |
"SHIVM and HDL on day three" | HDL HELD, SHIVM BROKE | HDL +0.84%, top turnover, third session in the top three. SHIVM −0.98% after two gains. |
"Bank exposure to microfinance wholesale lines — watch for any NRB directive" | DIFFERENT DIRECTIVE | NRB will absorb Rs 30 arba to manage excess liquidity. No circular yet on flood-affected loan classification or MFI wholesale provisioning. |
"Block data, four sessions dark" | FIFTH SESSION DARK | No Bulk Transaction capture again. Five consecutive sessions without block data, spanning a record-volume selloff and HATHY's collapse. |
"Gold versus deposit rates versus the tax" | GOLD BROKE | Down Rs 5,000 per tola, the largest single-day fall of the coverage but NRB is simultaneously draining Rs 30 arba of the liquidity that was the alternative. |
Top Stories
1. NRB drains another Rs 30 arba, the liquidity engine is being throttled
Nepal Rastra Bank will absorb Rs 30 arba from banks to manage excess liquidity in the market.
This is the single most important item in today's report and it goes to the core thesis of this coverage.
For three weeks this report has argued that the rally from the 31 August low was a liquidity event rather than a fundamental one. The evidence: repo at 4.25%, credit-to-deposit near 74% against a 90% ceiling, one-year FD at ~4.55%, savings at 2.9%, bank rates falling again in Ashwin, and remittance inflows of Rs 215.05 billion in a single month filling deposits that banks could not lend out. Turnover hit Rs 8.29 arab on 15 September, nearly double the previous coverage high.
Absorbing Rs 30 arba removes part of that surplus. It comes on top of the Rs 85 billion withdrawal already documented here. The mechanism is straightforward: NRB takes deposits out of the system through deposit-collection or reverse repo instruments, short-term rates firm up and the marginal rupee that was migrating into equities and real estate has somewhere else to sit.
Watch the credit-to-deposit ratio, not the index. That was the stated test on 15 September and it still is. As long as CD stays well below 90%, equities remain the default home for idle cash. If NRB's absorption starts moving it, the bid this market has been running on weakens mechanically.
The counterweight, and it is real: FNCCI is pressing the other way. The federation urged the government to withdraw VAT on electricity, citing rising business costs, a demand for stimulus at the same moment the central bank is tightening. And gold fell Rs 5,000 per tola today removing the most direct alternative for retail savings. The forces are now pulling in opposite directions rather than all pointing at equities.
2. HATHY: a third of its value gone in six sessions, and still no disclosure
Hathway Investment Nepal fell 10.58% to 405.00 a sixth consecutive decline while topping the volume table and taking Rs 19.99 crore of turnover.
The full sequence from 11 September, the day it rose on announcing up to Rs 40 crore of investment into a sugar mill and a hydropower project:
Date | Close | Change |
|---|---|---|
11 Sep | 609.00 | +5.56% |
17 Sep | 588.00 | −2.97% |
18 Sep | 499.80 | −15.00% |
23 Sep | 469.00 | −4.09% |
24 Sep | 452.90 | −3.43% |
28 Sep | 405.00 | −10.58% |
The volume profile changed on 24 September and intensified today. The first four declines came on unremarkable turnover. Then Rs 11.93 crore, now Rs 19.99 crore and the most-traded name in the market. A stock does not become the volume leader on its sixth consecutive fall unless size is exiting.
The precedent in this coverage is ENL, where the price collapsed limit-down two sessions before the six-shareholder sale filing was published and ENL fell another 9.92% today to 496.00, −20.0% from 10 September, with 913,099 shares still to come from seven holders over three months.
Treat HATHY as information not yet public. That has been this report's reading since 18 September and six more sessions of evidence support it.
3. Rs 9 arba into a new hydro project while another one goes offline
A Machhapuchchhre Bank-led consortium has provided a Rs 9 arba loan for the 63 MW Chhujung Khola project. On the same day, Sayapatri Hydropower's 2.5 MW project halted after flood damage to its transmission line.
The juxtaposition is the story. This report has tracked bank exposure to hydropower since Rs 115 billion was committed to Tila-1 and Tila-2 in a single week. Add Rs 9 arba today and the sector's bank funding keeps expanding into an environment where:
Twelve projects remain offline from the Bhotekoshi flood, with exports down from ~1,000 MW to ~650 MW.
TVCL carries Rs 8.2 billion of loans on ICRA negative watch after losing its 37 MW Upper Trishuli-3 'B' project entirely; it fell another 3.93% today.
Sagarmatha Jalabidhyut sits on BBB- with Watch with Negative Implication.
NEA the offtaker on essentially every listed PPA — has reported a 43% profit decline and is importing up to 654 MW from India for 18 hours daily heading into the low-water season.
Reconstruction is estimated near NPR 560 billion, against external aid of roughly Rs 5.3 billion.
No restoration timeline has been published for RHPL, CHCL or the 220 kV Trishuli-3 'B' substation.
No NRB circular on flood-affected loan classification after more than four weeks.
Sayapatri is a small project, but it is the first new flood casualty disclosed in over a week, and it establishes that damage is still surfacing a month after the event. HydroPower closed −1.03% today, the third-worst sector.
Separately, Rapti Hydro & General Construction received preliminary ERC approval to issue right shares at 1:0.2514 more equity supply into the same sector.
4. Gold falls Rs 5,000 in a day
Gold dropped Rs 5,000 per tola and silver Rs 145.
This is the largest single-day bullion move recorded in this coverage. The sequence has been volatile: gold crossed Rs 305,000 in mid-September, fell below Rs 300,000 on 17 September, rose Rs 1,700 on 22 September and has now dropped Rs 5,000.
Why it matters: gold is the direct competitor for the roughly 1.7 million active demat accounts' savings. With deposits at 2.9%, short-term equity gains newly taxed at 5%, and bullion now falling sharply, the relative-return calculation shifts back toward equities except that NRB is simultaneously withdrawing Rs 30 arba of the liquidity that funds them.
Note also that oil prices are rising as Iran tensions escalate, which pressures a net fuel-importing economy already running a merchandise trade deficit up 24.9% to Rs 148.74 billion monthly, with NOC absorbing higher IOC rates rather than passing them through.
5. Wagle in Doha with the AIIB: the reconstruction financing question
Finance Minister Swarnim Wagle met the AIIB President in Doha to discuss infrastructure investment.
Why it matters: this is the third senior external engagement this month after Wagle's New Delhi visit and Foreign Minister Khanal's talks with Jaishankar. The context is unambiguous: reconstruction after the Rasuwa flood is estimated near NPR 560 billion ($4 billion); external assistance to date totals roughly Rs 5.3 billion, under 1% of that; government revenue is running at 11.59% of annual target after two months; and Rasuwagadhi customs, worth around NPR 13.64 billion annually, remains impaired.
Multilateral infrastructure financing is the only realistic route to a reconstruction programme of that size that does not crowd out private credit. Anything concrete from these discussions would be the most consequential macro development available to this market. Nothing has been announced.
On the domestic fiscal side: Mechi Customs collected Rs 2 arba 83 crore in the first two months, and six bills were introduced in the Lower House today worth watching for any securities or banking legislation, given the NRB Act amendment cleared committee on 16 September while SEBON's promised Securities Act amendments still have no draft.
6. Bonus supply keeps arriving, and dividends keep closing
United Ajod Insurance (UAIL) bonus shares listed on NEPSE and three further stocks received price adjustments for bonus shares following Snow Rivers, Shangrila Development Bank, Synergy Power, United Modi and Aatmanirbhar Laghubitta in recent sessions.
Today was also the last trading day to secure dividends of three companies.
Why it matters: this report's refined rule is that the market pays for cash and does not pay for bonus. Cash dividends are 5 for 5 on producing an announcement-day move; KDL's bonus-dominant 8.9474% package produced −14.28%. Bonus listings are the mechanical end of the same thing: new shares arrive, the price adjusts, nothing of value is delivered.
The Ashwin cluster is still ahead: Reliance Spinning's 30% cash on Ashoj 22, GBIME and KDL on Ashwin 16, Nabil Investment Banking on Ashwin 20, Citizens Bank on Ashwin 28. With short-term gains taxed 150bp higher than long, the open question remains whether holders sit through book closure rather than selling into the announcement. Cash dividends are 0 for 5 on extending the move.
7. Rain, roads and the rest of the board
Rainfall disrupted major highways across the country and a landslide blocked the Manakamana road, though the cable car continues operating normally. This is the fourth week in which weather and road disruption have featured the Krishnabhir reopening after 18 days on 17 September was the one clear improvement, and Rasuwagadhi remains shut.
Corporate and governance: Tej Bahadur Chand stepped down from the Sanima Reliance Life board, Life Insurance closed −0.83%, with SRLI −0.70%. Niraj Sharma was appointed CEO of eSewa Limited. Syakar Trading signed an auto-loan agreement with NIC ASIA Bank for Honda cars another bank pushing loan demand in a system that cannot deploy its deposits. inDrive's financial literacy course reached 2,500 driver partners. Shivam Cement distributed warm clothes and educational materials to students.
Corporate Actions & Events
Company | Action | Detail |
|---|---|---|
Nepal Rastra Bank | Liquidity | To absorb Rs 30 arba from banks (on top of Rs 85 bn) |
Machhapuchchhre Bank (MBL) | Lending | Rs 9 arba consortium loan, 63 MW Chhujung Khola |
Sayapatri Hydropower | Operations | 2.5 MW project halted, flood damage to transmission line |
Rapti Hydro & Gen. Construction | Rights | ERC preliminary approval, 1:0.2514 |
United Ajod Insurance (UAIL) | Bonus listing | Bonus shares listed on NEPSE |
Three listed stocks | Price adjustment | Adjusted for bonus shares |
Three companies | Book closure | Last trading day to secure dividends today |
FNCCI | Policy | Urges withdrawal of VAT on electricity |
Sanima Reliance Life | Board | Tej Bahadur Chand steps down |
Syakar Trading / NIC ASIA | Business | Auto-loan agreement for Honda vehicles |
eSewa Limited | Management | Niraj Sharma appointed CEO |
Reliance Spinning Mills | Dividend | 30% cash · AGM Ashoj 22 |
Nabil Investment Banking | Dividend | 10% bonus + 11.05% cash · AGM Ashwin 20 |
Global IME Bank (GBIME) | Dividend | 10% (4% bonus + 6% cash), AGM Ashwin 16 |
Kalinchowk Darshan (KDL) | Dividend | 8.9474%, AGM Ashwin 16 |
Citizens Bank (CZBIL) | Book closure | 4% dividend, AGM Ashwin 28 |
Trishuli Jal Vidyut (TVCL) | Rating | Rs 8.2 bn loans on NEGATIVE WATCH · −3.93% today |
Sagarmatha Jalabidhyut | Rating | BBB-, Watch with Negative Implication |
Emerging Nepal (ENL) | Shareholder sales | 7 holders, 913,099 shares −9.92% today |
Himalayan Reinsurance (HRL) | Board | Chair still vacant, −1.90% today |
— | Legislation | Six bills introduced in the Lower House |
— | Tax | Advance tax on securities gains: 5% ≤365 days, 3.5% >365 days, at source |
What to Watch
1. The credit-to-deposit ratio, now that NRB is draining Rs 30 arba. The liquidity thesis said CD near 74% against a 90% ceiling keeps equities as the default home for idle cash. Rs 30 arba of absorption plus the Rs 85 billion already withdrawn is the first genuine test of that. Watch short-term rates and the weekly deposit-lending data, not the index.
2. 2,600, then 2,594. Thirteen and nineteen points below. 2,594 is the first tested level underneath and the market has broken a support on first test twice this month.
3. HATHY, thirteen sessions and −33.5%. Two consecutive sessions of heavy volume against a falling price Rs 11.93 crore, then Rs 19.99 crore as the volume leader. The absence of any filing after a third of the market value has gone is the most conspicuous gap in this market right now.
4. Does anything rise more than 1.3%? A gainer table where second place is +1.27% is not a market pausing, it is a market without buyers. A normal gainer table, three or four names above 3% with volume behind them would be the first sign of a bid returning.
5. HDL on day four. Three consecutive sessions in the top three by turnover, Rs 91.53 crore cumulative, price 1,278.30 → 1,312.00 → 1,323.00. Twenty rotations have failed in this coverage, most on day three. HDL has cleared that.
6. Bank exposure to hydro against the flood file. Rs 9 arba into Chhujung Khola on the day Sayapatri went offline and TVCL fell again on Rs 8.2 billion of watch-listed debt. Watch for a second rating action, any NRB circular on flood-affected loan classification, and whether more small projects disclose damage.
7. Block data, five sessions dark. No Bulk Transaction capture since 16 September. HATHY's Rs 19.99 crore, the record-volume selloff of 23 September, and HDL's three-session run are all unexamined at block level. This remains the most valuable missing input in the report.
8. AIIB, and anything concrete on reconstruction financing. NPR 560 billion needed, Rs 5.3 billion pledged, revenue at 11.59% of target. Wagle is in Doha. Nothing has been announced, and this gap is the largest unpriced macro risk in the market.
Disclaimer
This report has been prepared by Nepalytix for informational and educational purposes only and does not constitute investment advice, an offer, or a solicitation to buy or sell any securities.
The information contained in this report is based on sources believed to be reliable; however, Nepalytix does not guarantee its accuracy, completeness, or timeliness. Opinions, estimates, and projections expressed herein are those of the authors as of the date of publication and are subject to change without notice.
Investing in securities involves risks, including the possible loss of principal. Past performance is not indicative of future results. Readers are advised to conduct their own independent research and consult with a qualified financial advisor before making any investment decisions.
Nepalytix and its contributors may hold positions in the securities discussed in this report at the time of publication or thereafter.
Neither Nepalytix nor any of its affiliates accept any liability for any loss arising from the use of this report or its contents.