NEPSE Recovers to 2624 as SBL Leads Market Activity
NEPSE rose 11.93 points to 2,624.36 as the market absorbed the new securities tax while Siddhartha Bank’s 20% dividend proposal drove the day’s biggest trading activity.
Markets Today
The 30-Second Read
NEPSE closed 2,624.36, up 11.93 (+0.45%), the first full session after the Cabinet's new advance tax on securities gains was made public. The market did not sell off. It recovered 56% of yesterday's decline.
Breadth back to 2.08 (177 advancers, 85 decliners, 20 unchanged, the highest unchanged count of the coverage). From 0.19 yesterday.
Siddhartha Bank proposed a 20% dividend and finished top of both activity tables: +3.71%, Rs 33.62 crore turnover, 7.57 lakh shares. The cash-dividend thread is now the most reliable signal in this dataset.
Turnover Rs 5.50 arab, a third consecutive heavy session. Scrips traded fell to 339, the lowest of the coverage, more money through fewer names.
Krishnabhir reopened to two-way traffic after 18 days. The Prithvi Highway blockage that doubled freight costs and pushed Kathmandu LPG 38.6% above the official price is clearing.
Gold fell back below Rs 300,000 per tola, one session after rising Rs 1,700. The competition for the marginal rupee just tilted back toward equities.
RSML fell a third consecutive session to 2,745.00, now −8.3% from its 2,993 peak while still fourth by turnover.
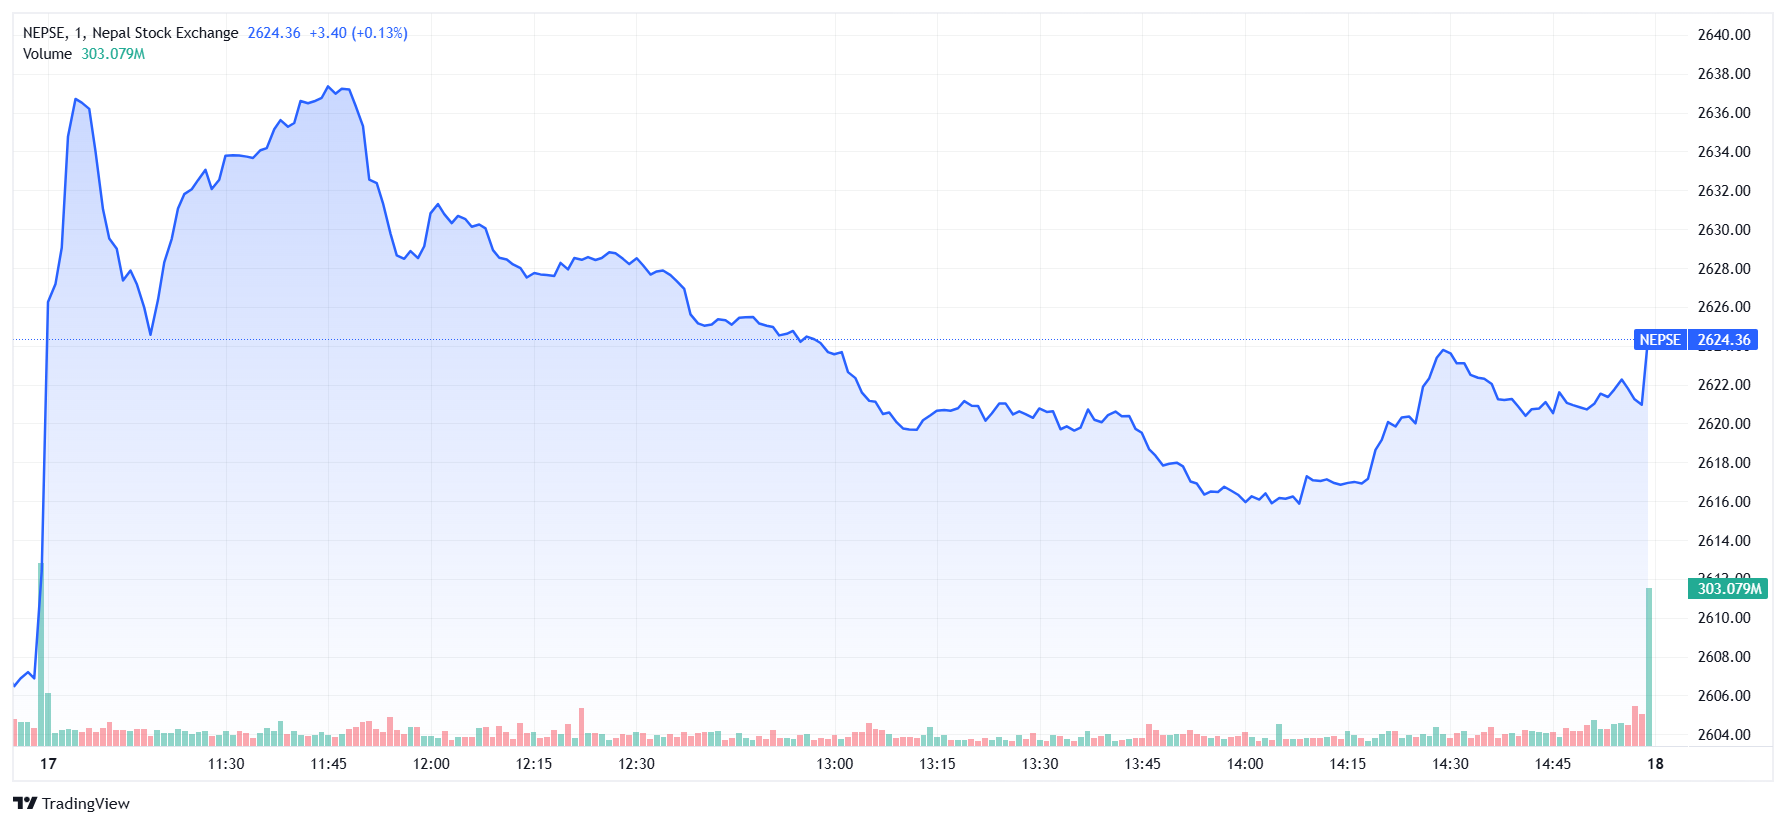
Still below the 2,629–2,633 zone, 4.64 points short of re-entering it.
Yesterday's report set a clean binary: if today opened sharply lower, the 21-point decline was anticipation of the tax and the news was still working through; if it opened flat or higher, the market had decided a 5%/3.5% advance tax was survivable.
It went up.
NEPSE closed 2,624.36, up 11.93 points (+0.45%), on Rs 5.50 arab, 1.36 crore units and 51,728 transactions across 339 scrips. Advancers 177, decliners 85, unchanged 20, an A/D of 2.08.
The market recovered 56% of yesterday's 21.19-point loss with breadth back above parity. Eleven of twelve captured sectors closed green, with only Investment red at −0.18%. That is the answer to the tax question: the market absorbed it.
Two readings are possible and both should be held. Either the selling on 16 September was anticipation and today is relief now that the terms are known, 3.5% on holdings over 365 days, 5% on 365 days or less, collected at source by NEPSE. Or the tax simply is not large enough to change behaviour in which case its structural effect on churn will show up over weeks in turnover and holding patterns rather than in a single session. What is now ruled out is the panic scenario.
The composition is unusual and worth pausing on. Scrips traded fell to 339, the lowest count of the coverage and unchanged names rose to 20, the highest. Yet turnover rose slightly to Rs 5.50 arab from Rs 5.39. More money moved through fewer names with more names not moving at all. That is a narrowing, selective tape, the opposite of Tuesday's 265-advancer melt-up.
And the leadership changed to banks. Siddhartha Bank topped both the volume and turnover tables at +3.71% with Rs 33.62 crore, 6.1% of the entire market after proposing a 20% dividend. LSL rose 2.58% on 3.73 lakh shares. Banking closed +0.58%. Meanwhile SANIMA fell 2.36%, one of the day's worst, so this was not a sector bid, it was a dividend bid.
Index Snapshot
NEPSE Index: 2,624.36(11.93, 0.45%)
Turnover: Rs 5.50 arab
Volume: 1.36 crore units
Transactions: 51,728
Scrips traded: 339
Sectoral Indices Performance
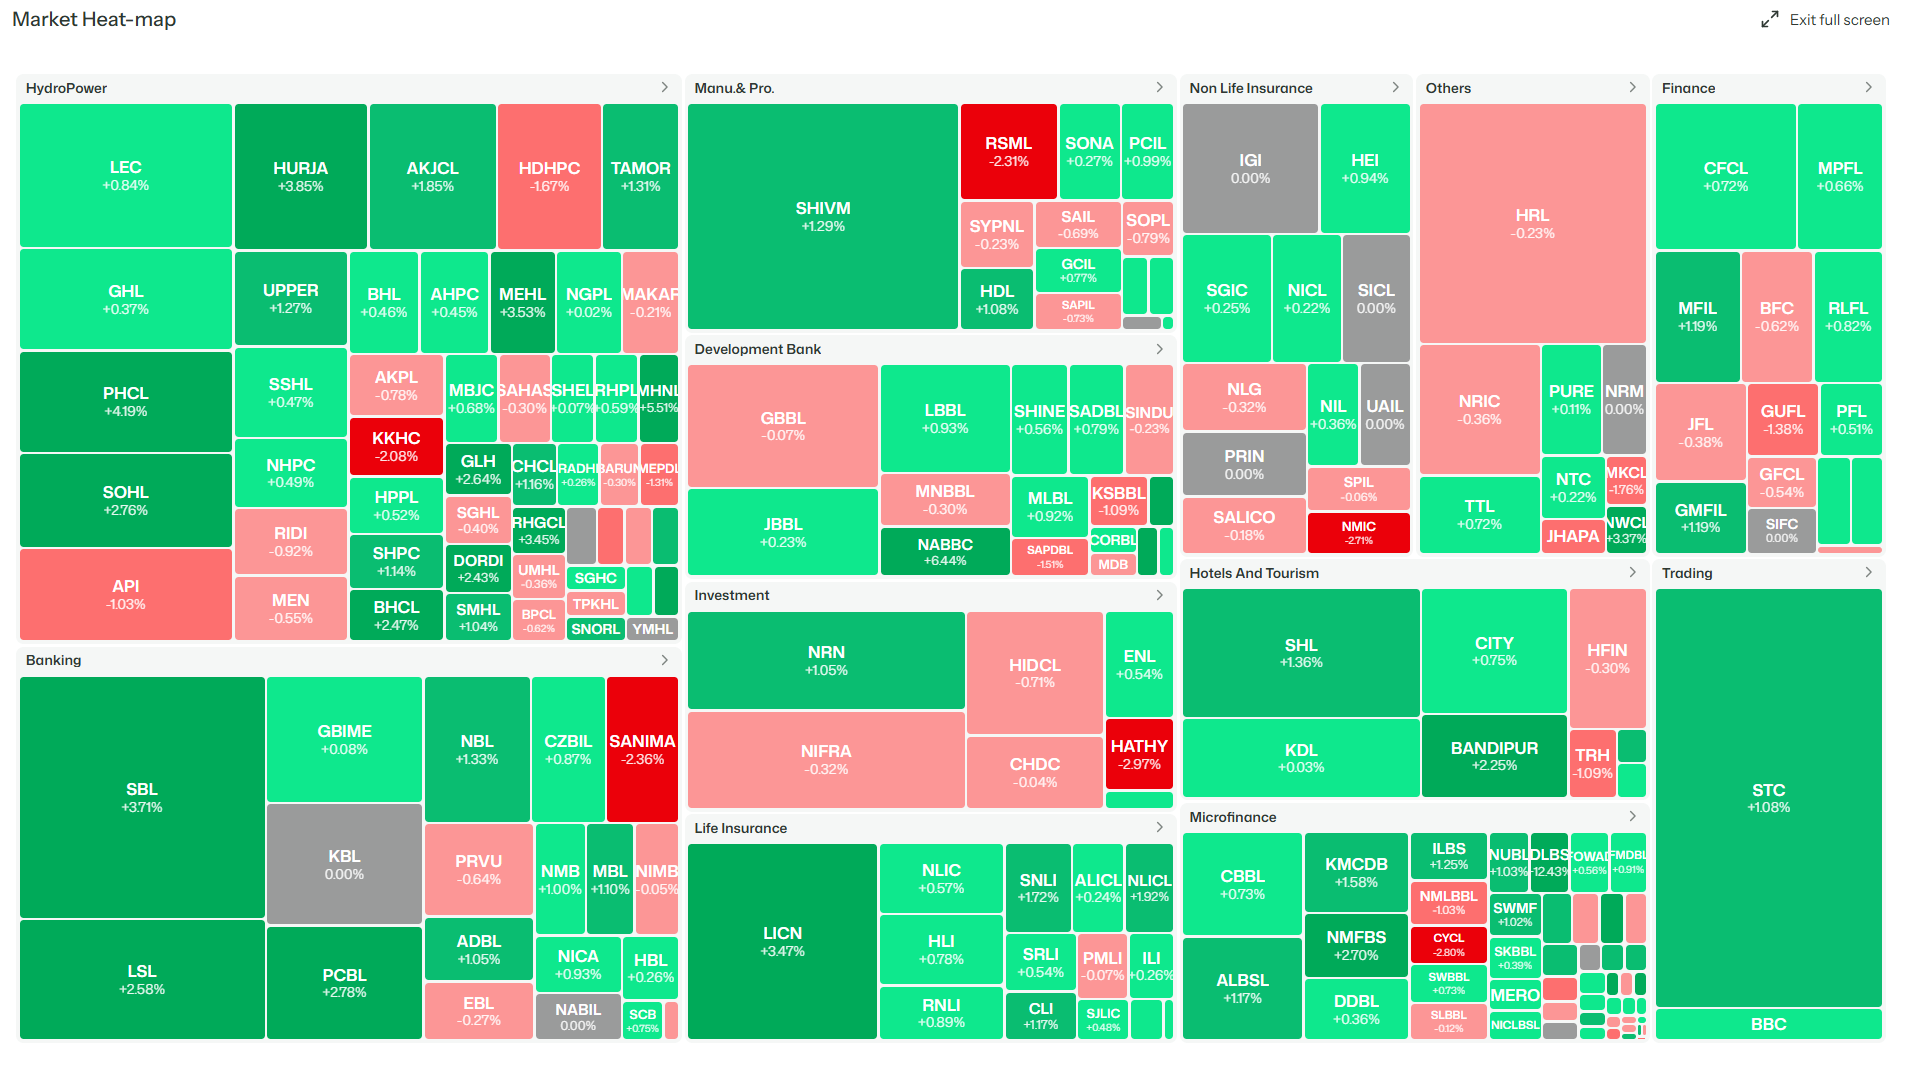
Eleven green, one red, spread of 1.26 points. Float (180.58, +0.53%) is a broad index, not a sub-index.
Life Insurance leads at +1.08% on LICN +3.47%, SNLI +1.72%, CLI +1.17% and HLI +0.78%. Non-Life is effectively flat at +0.05%, the two insurance sectors have now diverged for the first time in a fortnight, having moved together through the entire Bhotekoshi claims sequence.
Investment is the only red sector and it is a two-stock story: HATHY −2.97% and HIDCL −0.71%, against NRN +1.05% and ENL +0.54%.
Market Breadth
Metric | Count |
|---|---|
Advancers | 177 |
Decliners | 85 |
Unchanged | 20 |
Live universe | 282 |
A/D ratio | 2.08 |
A/D series (last ten captured sessions): 2.47 → 0.39 → 0.34 → 7.65 → [gap] → 22.08 → 0.19 → 2.08
The 20 unchanged names are the highest count of the coverage, and combined with 339 scrips traded also a coverage low, they say the same thing: a meaningful slice of the market simply did not participate today. In a tape that has swung from 22.08 to 0.19 to 2.08 in three sessions, names standing still is arguably the healthiest signal available.
2.08 is a normal reading. After a record high and a near-record low in consecutive sessions, this is the first breadth print in a week that does not require an asterisk.
Winners & Losers
Top Gainers
Stock | Sector | LTP | % |
|---|---|---|---|
DLBS | Microfinance | 1,248.00 | +12.43% |
NABBC | Development Bank | 793.00 | +6.44% |
MHNL | HydroPower | 268.00 | +5.51% |
PHCL | HydroPower | 323.00 | +4.19% |
USLB | Microfinance | 1,070.00 | +3.98% |
HURJA | HydroPower | 266.90 | +3.85% |
SBL | Banking | 447.00 | +3.71% |
MEHL | HydroPower | 264.00 | +3.53% |
SPC | HydroPower | 406.00 | +3.49% |
LICN | Life Insurance | 806.00 | +3.47% |
SBL is the only name in this table backed by the heaviest money in the market: top of both activity tables on a 20% dividend proposal. PHCL, HURJA and LICN also appear in an activity table so four of ten gainers have volume behind them which is unusually good for this tape.
NABBC has now risen two consecutive sessions: +6.37% yesterday, +6.44% today from 745.00 to 793.00, a 6.4% two-day gain. It appears in neither activity table so treat the size with caution but it is one of only two names currently holding a direction.
DLBS +12.43% is the largest single move on the board and appears in no activity table.
Top Losers
Stock | Sector | LTP | % |
|---|---|---|---|
HATHY | Investment | 588.00 | −2.97% |
CYCL | Microfinance | 1,458.00 | −2.80% |
SHLB | Microfinance | 1,320.20 | −2.78% |
ULHC | HydroPower | 318.00 | −2.75% |
NMIC | Non Life Insurance | 836.60 | −2.71% |
SANIMA | Banking | 364.30 | −2.36% |
RSML | Manu. & Pro. | 2,745.00 | −2.31% |
NYADI | HydroPower | 361.00 | −2.14% |
KKHC | HydroPower | 282.00 | −2.08% |
SIPD | HydroPower | 588.00 | −2.00% |
The loser table is shallow, worst name down 2.97%, nothing near a circuit.
RSML is down a third consecutive session: 2,879 → 2,810 → 2,745. From its 2,993 peak that is −8.29%. It remains fourth by turnover at Rs 17.10 crore so this is heavy selling, not drift. RSML is the only name in the coverage to have held a three-day move in both directions, three up in early September, three down now.
HATHY −2.97% completes the round trip on the Rs 40 crore capital-deployment story that lifted it 5.56% on 11 September. Capital-allocation news is back to 0 for 7 on a sustained basis.
KKHC fell 2.08% after rising 2.86% yesterday, and ULHC fell 2.75%, the name that has now swung 300 → 260 → 299 → 320 → 318 across five sessions.
Turnover & Volume Leaders
Most Active by Turnover
Stock | LTP | % | Turnover |
|---|---|---|---|
SBL | 447.00 | +3.71% | Rs 33.62 Cr |
SHIVM | 685.00 | +1.29% | Rs 27.27 Cr |
SOHL | 671.00 | +2.76% | Rs 23.85 Cr |
RSML | 2,745.00 | −2.31% | Rs 17.10 Cr |
NRN | 1,455.00 | +1.05% | Rs 14.53 Cr |
LEC | 252.10 | +0.84% | Rs 13.69 Cr |
PHCL | 323.00 | +4.19% | Rs 12.25 Cr |
API | 335.60 | −1.03% | Rs 11.82 Cr |
AKJCL | 352.90 | +1.85% | Rs 11.67 Cr |
LICN | 806.00 | +3.47% | Rs 11.17 Cr |
Most Active by Volume
SBL (7.57 L, +3.71%), LEC (5.43 L, +0.84%), SHIVM (3.97 L, +1.29%), GHL (3.87 L, +0.37%), PHCL (3.84 L, +4.19%), LSL (3.73 L, +2.58%), SOHL (3.56 L, +2.76%), API (3.50 L, −1.03%), HURJA (3.46 L, +3.85%), AKJCL (3.32 L, +1.85%)
SBL at Rs 33.62 crore is 6.1% of the market, and it got there on a dividend proposal announced the same day. This is the cleanest single-name cause-and-effect in the entire coverage.
Concentration has eased further. On 10 September LEC alone took 11.4% of turnover; today the top name takes 6.1% and the top five roughly 21% of a Rs 5.50 arab pie. Spread across more money is healthier than the 25.6% top-four reading of a week ago.
SOHL +2.76% on Rs 23.85 crore is the third-largest turnover and a genuine mover, one of the few hydro names with size behind a gain.
Two banks in the volume table (SBL, LSL), both up, while SANIMA fell 2.36%. Banking participation is dividend-selective, not sector-wide.
Signal Scorecard
Prior call | Status | What happened |
|---|---|---|
"Does the tax get priced tomorrow, or was it priced today?" | ABSORBED | Index +11.93, A/D 2.08, eleven of twelve sectors green. The panic scenario is ruled out. Either 16 September was anticipation, or the tax is too small to change behaviour, the structural effect will now show in turnover and holding patterns over weeks, not in a print. |
"2,600, then 2,594" | NEITHER TESTED | Market went up. 2,600 held comfortably; the low of the range was never approached. |
"The 2,629–2,633 zone needs a second attempt" | NOT YET | Closed 2,624.36, still 4.64 points below the bottom of the band. Second attempt still pending. |
"Block direction — more blocks on red prints would mean holders exiting into the tax" | NO DATA | No Bulk Transaction capture was provided for this session. The block question is unresolved and carries forward. |
"The AGM calendar against the new tax" | FIRST AGM APPROVAL | Kamana Sewa Bikas Bank approved its 15% cash dividend at the 20th AGM, the first dividend to move from proposal to approval in this coverage. |
"Cash dividends 3 for 3" | 4 FOR 4 | SBL proposed 20% and took the whole tape: +3.71%, top of both activity tables, 6.1% of turnover. The single strongest dividend reaction recorded here. |
"Deposit rates versus the tax versus gold" | GOLD REVERSED | Gold fell back below Rs 300,000 per tola after rising Rs 1,700 the previous session. One of the three competitors for the marginal rupee just weakened. |
"SEBON pre-disclosure — watch for the next one" | FOURTH CASE, AND UHEWA'S SECOND | Two Upper Hewakhola shareholders filed to sell 134,601 shares. UHEWA was the first-ever test of this rule on 1 September. |
"The supply chain / LPG at 38.6% above official price" | CLEARING | Krishnabhir reopened to two-way traffic after 18 days. |
"Capital allocation 1 for 7" | BACK TO 0 | HATHY −2.97%, completing the round trip on the Rs 40 crore deployment story. |
Top Stories
1. Siddhartha Bank proposes 20% and the dividend thread becomes the strongest signal in the dataset
Siddhartha Bank (SBL) proposed a 20% dividend for FY 2082/83. The stock closed 447.00, +3.71% topping both the volume table (7.57 lakh shares) and the turnover table (Rs 33.62 crore, 6.1% of the entire market).
Set that against the running scoreboard this report has built:
Announcement | Composition | Reaction |
|---|---|---|
SBL 20% | Split not yet disclosed | +3.71%, top of both tables |
GBBL 20% | Proposed | +2.45%, top of tape |
GBIME 10% | 6% cash + 4% bonus | +4.13% |
Himalayan Capital 80-20 15% | Cash | Record unit volume |
MBL 6% | Proposed | +0.80% |
KDL 8.9474% | 8.5% bonus + 0.4474% cash | −14.28% |
Cash dividends: now 4 for 4. Bonus-dominant: 0 for 1. Earnings: 0 for 6. Capital allocation: 0 for 7.
This market prices one thing reliably, and it is cash in hand. The practical consequence is that the AGM and board-meeting calendar is the highest-value event list available and the move happens on announcement day.
The new tax sharpens this. With short-term gains taxed at 5% versus 3.5% beyond 365 days, the incentive to hold through book closure rather than trade around it has just increased by 150 basis points. Watch whether dividend names now hold their announcement-day gains for a second and third session, historically they have not.
And the first proposal converted to an approval today: Kamana Sewa Bikas Bank approved its 15% cash dividend at the 20th AGM. KSBBL closed −1.09% which is the expected pattern, the move happens at proposal, not approval.
Also announced: Bikash Hydropower proposed 10.5263% for FY 2082/83 with the bonus-cash split disclosed.
2. The tax absorbed and what to actually watch now
The Cabinet's advance tax on securities gains was published at 5:59 PM on 16 September: 3.5% for natural persons on holdings above 365 days, 5% on holdings of 365 days or less, collected at source by the entity performing the functions of the securities market.
Today was its first full session and the market rose 0.45% with breadth at 2.08.
The honest reading is that a single session settles the panic question and nothing else. A 150 basis point differential does not reprice a market overnight; it changes incentives at the margin over months. The three things that would actually show it working:
First, turnover normalising downward. Four of the last five sessions have run Rs 5.39–8.29 arab against a coverage average near Rs 3.7 arab. If short-term trading carries a 5% levy at source, the sustainable run-rate should fall.
Second, the churn pattern breaking. For a month this report has documented six of ten gainers becoming losers the next day, four consecutive sessions of it at one point. That is precisely the behaviour now taxed at the higher rate. Today already looks different, the loser table is shallow, 20 names went unchanged and only three of yesterday's movers reversed hard.
Third, holding through book closure. With Reliance Spinning's 30% cash book closure already set, GBIME and KDL both at Ashwin 16 and Nabil Investment Banking at Ashwin 20, the next fortnight gives a direct test.
One structural note. Collection at source means cash leaves the account on disposal rather than at assessment. Against Rs 166.50 billion of margin lending, 72% of it in accounts above Rs 1 crore that tightens working capital on every round trip, a quiet drag that compounds for the most active accounts.
3. Krishnabhir reopens after 18 days, the supply chain unwinds
Two-way traffic resumed at Krishnabhir in Dhading after 18 days.
This is the blockage that has run through this coverage since late August. The chain: Rasuwagadhi closed with 176 containers stranded at Kerung and roughly 40 km of the 56 km Bidur–Rasuwagadhi road destroyed; freight per container roughly doubling from NPR 175,000–200,000 to NPR 300,000–400,000; the Prithvi Highway blocked at Krishnabhir turning a three-hour run into nearly five; Salt Trading forced to fill STC cylinders at private plants on about 2% of the NOC allocation; NOC halting commercial LPG supply through Valley depots; and cooking gas selling at Rs 3,000 against a government-fixed Rs 2,165, 38.6% above the official rate.
Why it matters: Krishnabhir reopening does not restore Rasuwagadhi, but it restores the main artery between Kathmandu and the west. Watch LPG pricing and Hotels & Tourism, the sector closed +0.85% today with SHL +1.36%, CITY +0.75% and BANDIPUR +2.25% and it has been carrying festival-quarter energy costs. If the Rs 3,000 cylinder price starts converging back toward Rs 2,165 over the next week, that is the real signal.
Rasuwa Customs collected around NPR 13.64 billion last fiscal year and that line remains impaired while Rasuwagadhi stays shut.
4. Gold breaks back below Rs 300,000, the allocation fight tilts
Gold fell below three lakhs per tola, with silver around Rs 4,600. That is a reversal one session after gold rose Rs 1,700 and silver Rs 85.
Why it matters: yesterday's report framed the next fortnight as a three-way contest for the marginal rupee, deposit rates falling again in Ashwin (one-year FD ~4.55%, savings 2.9%, CD ratio ~74% against a 90% ceiling), a new 5% tax on short-term equity gains and gold climbing. Gold just weakened.
Two of the three forces now point toward equities. The liquidity engine that drove Rs 8.29 arab of turnover on 15 September has not been switched off it has been mildly taxed and its main alternative just got less attractive.
5. Revenue at 11.59% of target, and Wagle goes to Delhi
The government collected Rs 183.20 billion in the first two months of FY 2083/84, 11.59% of the annual target.
Why it matters: two months is one-sixth of the year, so 11.59% is running behind a straight-line pace. This is the fiscal context for everything else. Reconstruction after the Rasuwa flood is estimated near NPR 560 billion ($4 billion). Rasuwa customs revenue is impaired. NOC is absorbing higher IOC rates rather than passing them through. And the government has just added an advance tax on securities gains which whatever its market-structure rationale is also a revenue measure arriving in a year that is starting slowly.
Finance Minister Wagle has travelled to New Delhi for economic discussions. Given that India approved up to 654 MW of power supply to Nepal for 18 hours daily on 15 September, and that reconstruction financing is the largest unanswered question in this market, the agenda matters. Separately, 33 winners of the Bhadra taxpayer incentive programme are to be announced.
6. Upper Hewakhola: the fourth pre-disclosure, and the second at the same company
Two shareholders of Upper Hewakhola Hydropower have filed to sell 134,601 shares.
UHEWA was the first-ever test of SEBON's rule requiring 5%-plus holders to notify before selling, Sudip Ghimire filed on 1 September to sell 452,533 shares (~7.9% of the company) over three months and the stock closed +0.17% the next session.
The scorecard across four cases is genuinely mixed: UHEWA dampened (+0.17%); ENL front-ran (limit-down two sessions before its six-holder filing was published, cumulative −27.7%, now a 913,099-share overhang across seven holders); KDL closed −1.66% on the day its major shareholders filed and UHEWA again today.
The pattern that is emerging is not about the rule, it is about size. UHEWA's filings are 452,533 and 134,601 shares and barely moved it. ENL's 913,099 across seven holders crushed it. The market prices the depth of the exit not the fact of disclosure.
7. Flood relief goes corporate and lawmakers lose patience
Lawmakers asked the government to immediately distribute relief materials to flood-hit people which is a signal that distribution is lagging.
Corporate contributions kept arriving: Garima Bikas Bank Rs 1.01 crore, Xiaomi Nepal 200 relief sets, Food Empire Singapore $20,000 through the chamber and a promotional scheme where a Rs 1,000 payment to the PM Relief Fund earned one customer a Rs 100,000 prize. SEBON separately cleared capital market firms to use CSR funds for disaster relief on 16 September.
Why it matters: against a reconstruction estimate near NPR 560 billion, the entire corporate relief effort across this coverage: Rs 1.01 crore here, Rs 1.11 crore there, $5 million from ADB remains a rounding error. The parliamentary pressure is the more useful signal: it means the fiscal response is visibly behind in a year running at 11.59% of revenue target.
8. Corporate and banking flow
Aatmanirbhar Laghubitta bonus shares were listed on NEPSE, new supply in a Microfinance sector that closed +0.55%. Muktinath Bikas Bank signed an MoU with Karma Residencies for home loan facilities, notable given NRB's data showing real estate transactions up 4.74% in FY 2082/83 and the liquidity surplus pushing banks to find lending demand. Nabil Bank opened applications for its seventh SSE Fellowship cohort. MetLife Nepal GM Nirmal Kajee Shrestha received an Asian Professional Achievement Award. The Nepal-Japan 70th anniversary cultural festival is set for 22 November.
Corporate Actions & Events
Company | Action | Detail |
|---|---|---|
Siddhartha Bank (SBL) | Dividend | 20% proposed FY2082/83, stock +3.71%, top of both tables |
Kamana Sewa Bikas Bank (KSBBL) | Dividend APPROVED | 15% cash approved at 20th AGM, first approval of the coverage |
Bikash Hydropower | Dividend | 10.5263% proposed, FY2082/83 |
Upper Hewakhola (UHEWA) | Shareholder sales | Two shareholders, 134,601 shares (second UHEWA filing) |
ICRA Nepal | Dividend | 62.50% proposed, 14th AGM |
Reliance Spinning Mills | Dividend | 30% cash · book closure set, AGM Ashoj 22 |
Snow Rivers | Dividend | 10.5263%, 5th AGM |
Citizens Bank (CZBIL) | Dividend | 4% proposed |
Kumari Bank | Dividend | 2.1053% cash |
Nabil Investment Banking | Dividend | 10% bonus + 11.05% cash, AGM Ashwin 20 |
Global IME Bank (GBIME) | Dividend | 10% (4% bonus + 6% cash), AGM Ashwin 16 |
Kalinchowk Darshan (KDL) | Dividend + sales | 8.9474% · AGM Ashwin 16 · major shareholders selling |
Aatmanirbhar Laghubitta | Bonus listing | Bonus shares listed on NEPSE |
Muktinath Bikas Bank (MNBBL) | Business | MoU with Karma Residencies for home loans |
Garima Bikas Bank (GBBL) | CSR | Rs 1.01 crore for Bhotekoshi flood victims |
Emerging Nepal (ENL) | Shareholder sales | 7 holders, 913,099 shares, 3-month window |
Trishuli Jal Vidyut (TVCL) | Rating | Rs 8.2 bn loans on NEGATIVE WATCH |
Sagarmatha Jalabidhyut | Rating | BBB-, Watch with Negative Implication |
Himalayan Reinsurance (HRL) | Board | Chair still vacant |
Shikhar Power Development | Lock-in expiry | 1.11 lakh units, Ashwin 2, 2083 |
— | Tax | Advance tax on securities gains: 5% ≤365 days, 3.5% >365 days, at source |
What to Watch
1. The 2,629–2,633 zone, second attempt 4.64 points away. It rejected the biggest single-day gain of the coverage on Tuesday. Clearing it on a second, quieter attempt would be more meaningful than Tuesday's spike was, because it would come without a record-breadth blow-off behind it.
2. Does SBL hold its dividend gain for a second session? Cash dividends are 4 for 4 on announcement day and 0 for 4 on holding the move. GBIME went +4.13% then +0.04%. GBBL went +2.45% then faded. With short-term gains now taxed 150bp higher, this is the first dividend announcement to face the new incentive structure. If SBL holds, the tax is already changing behaviour.
3. Turnover's sustainable level. Rs 5.50 arab on 339 scrips, the fewest of the coverage with 20 unchanged, the most. Money is concentrating into fewer names. Watch whether turnover settles toward Rs 4 arab as the tax bites or holds above Rs 5 arab because the deposit surplus overwhelms it.
4. RSML on day four, downward. Three consecutive declines, −8.29% from the 2,993 peak, still fourth by turnover at Rs 17.10 crore. It is the only name in this coverage to have held three-day moves in both directions. No block data available today, the tell will be whether blocks reappear against the falling price.
5. LPG pricing after Krishnabhir. Two-way traffic is back after 18 days. Cooking gas at Rs 3,000 against an official Rs 2,165 is the metric. Convergence over the next week validates the supply-chain repair; persistence says Rasuwagadhi's closure is the binding constraint, not the highway.
6. Wagle in Delhi. India has approved 654 MW of supply for 18 hours daily, reconstruction needs roughly NPR 560 billion and revenue is running at 11.59% of target after two months. Anything concrete on financing or power trade from these discussions is the most consequential macro item on the calendar.
7. The Ashwin AGM cluster. GBIME and KDL on Ashwin 16, Nabil Investment Banking on Ashwin 20, Reliance Spinning on Ashoj 22 plus Reliance's 30% cash book closure already set. Kamana Sewa's approval today showed the move happens at proposal, not approval so watch the proposals still to come, not the AGMs themselves.
Disclaimer
This report has been prepared by Nepalytix for informational and educational purposes only and does not constitute investment advice, an offer, or a solicitation to buy or sell any securities.
The information contained in this report is based on sources believed to be reliable; however, Nepalytix does not guarantee its accuracy, completeness, or timeliness. Opinions, estimates, and projections expressed herein are those of the authors as of the date of publication and are subject to change without notice.
Investing in securities involves risks, including the possible loss of principal. Past performance is not indicative of future results. Readers are advised to conduct their own independent research and consult with a qualified financial advisor before making any investment decisions.
Nepalytix and its contributors may hold positions in the securities discussed in this report at the time of publication or thereafter.
Neither Nepalytix nor any of its affiliates accept any liability for any loss arising from the use of this report or its contents.