NEPSE Reverses After Record Rally as New 5% Securities Tax Looms
NEPSE fell 21.19 points after yesterday’s record rally with breadth collapsing as the index was rejected at 2,629–2,633.
The 30-Second Read
NEPSE closed 2,612.42, down 21.19 (−0.80%), giving back 44% of yesterday's record +48.57 and getting rejected on the first test of the 2,629–2,633 zone the old support band that broke on 18 August.
Breadth collapsed from 22.08 to 0.19. Yesterday: 265 advancers, 12 decliners. Today: 42 advancers, 225 decliners. That is the most violent one-session breadth reversal in the entire coverage, by a wide margin.
At 5:59 PM nearly three hours after the close, the Cabinet made public a new advance tax on securities gains: 5% on holdings of 365 days or less, 3.5% on holdings over 365 days collected at source by NEPSE. The market fell before this was published. The tax hits tomorrow's session, not today's.
ICRA put Trishuli Jal Vidyut's Rs 8.2 billion of loans on negative watch over the flash flood damage. This report has flagged a TVCL rating action as overdue since 3 September. It arrived fourteen days after the total-loss disclosure.
Turnover Rs 5.39 arab down 35% from yesterday's Rs 8.29 arab but still the second-highest of the coverage.
HDHPC was the whole tape's bright spot: +5.31%, Rs 37.96 crore turnover (7.0% of the market), 16.64 lakh shares, top of both activity tables.
More dividends and bigger ones: ICRA Nepal 62.50%, Reliance Spinning Mills 30% cash, Citizens Bank 4%, Kumari Bank 2.1053%.
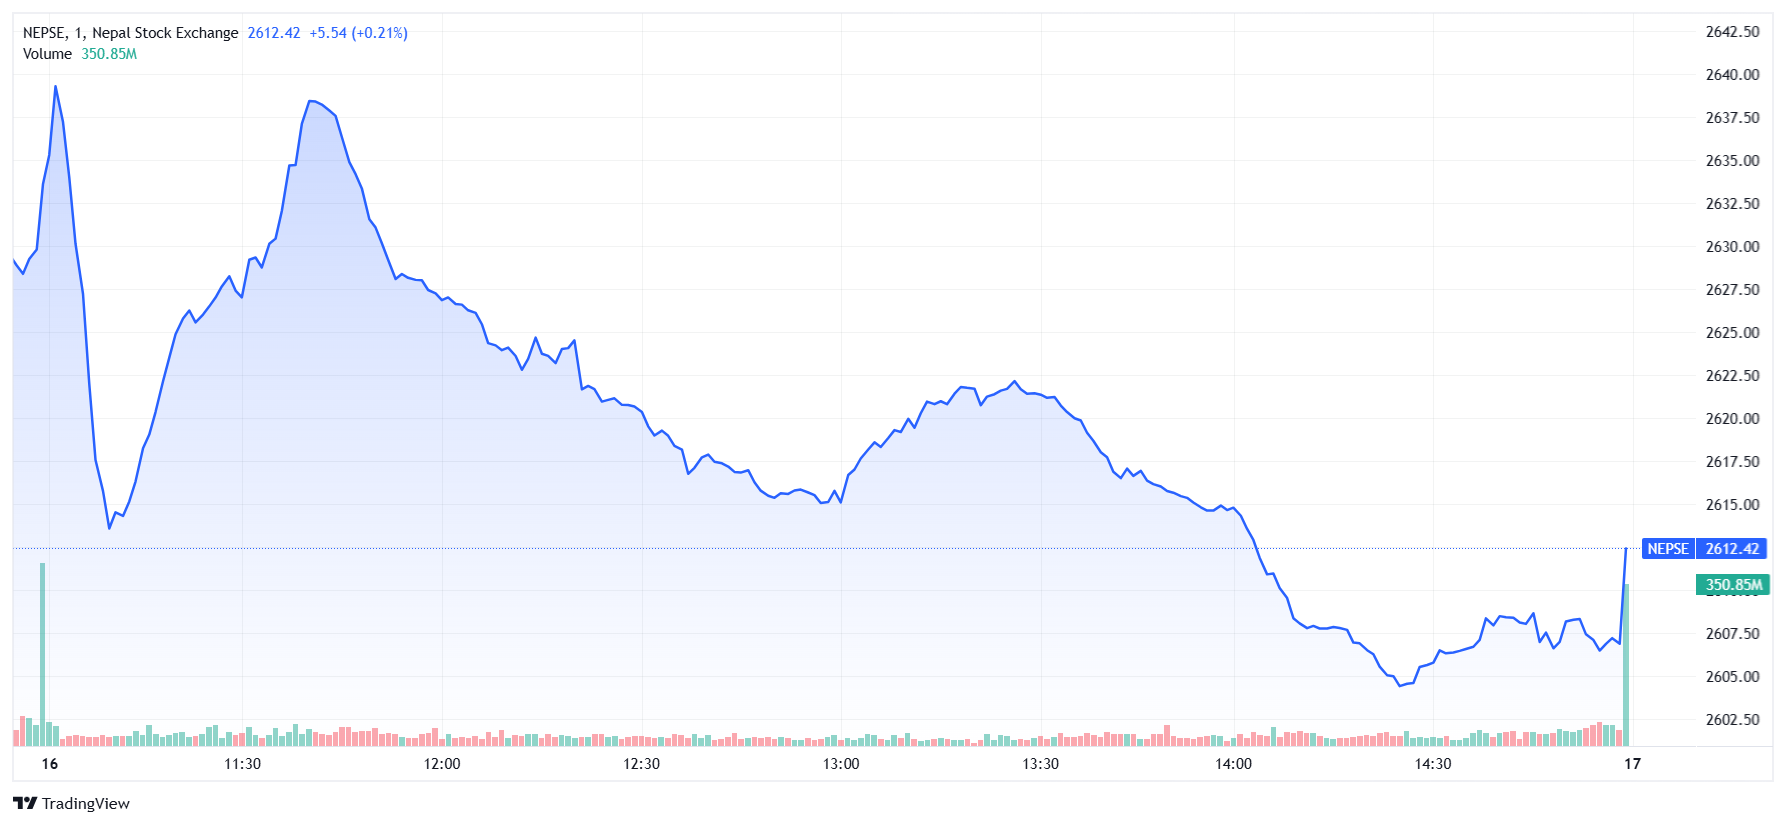
Yesterday this report said the 2,629–2,633 band was where the rally would either confirm or stall, because it had held four tests as support before breaking on 18 August and had now become resistance. It stalled on the first test.
NEPSE closed 2,612.42, down 21.19 points (−0.80%) on Rs 5.39 arab, 1.51 crore units and 55,831 transactions across 350 scrips. Advancers 42, decliners 225, unchanged 15, an A/D of 0.19.
The breadth swing is the number that matters. In one session the market went from 265 advancers and 12 decliners to 42 advancers and 225 decliners. Nothing in twenty-five sessions of this coverage comes close. The prior worst single-session reversals were 2.47 → 0.39 and 1.24 → 0.08; this is 22.08 → 0.19. Yesterday 94% of the quoted universe rose; today 80% fell.
Every captured sector closed red, in a tight band from Manufacturing at −0.52% to Hydropower at −1.04%. Nothing was spared and nothing was singled out, the mirror image of yesterday.
Large caps did not protect anyone. Sensitive fell 0.80%, exactly in line with the index and Sensitive Float fell 0.84%. Yesterday the quality end outperformed on the way up; today it matched on the way down.
Turnover stayed heavy. Rs 5.39 arab is down 35% from yesterday's record but remains the second-highest reading of the coverage, and transactions at 55,831 are the second-highest too. This was not an absence of buyers. It was a broad decision to sell.
Now the timing question, and it matters. The Cabinet's decision on advance tax was published after the market closed at 3:00 PM. The decline came first. Either the decision leaked into the trading session, or today was ordinary profit-taking after the biggest single-day gain in the coverage and the tax lands tomorrow morning as fresh news. This report cannot distinguish between those two from the data available and will not pretend to. What is certain is that tomorrow opens with a new tax on the table that today's sellers may or may not have known about.
Index Snapshot
Index | Close | % |
|---|---|---|
NEPSE | 2,612.42 | −0.80% |
Sensitive | 463.68 | −0.80% |
Sensitive Float | 156.58 | −0.84% |
Turnover Rs 5.39 arab
Volume 1.51 crore units
Transactions 55,831
Scrips traded 350
Sectoral Indices Performance
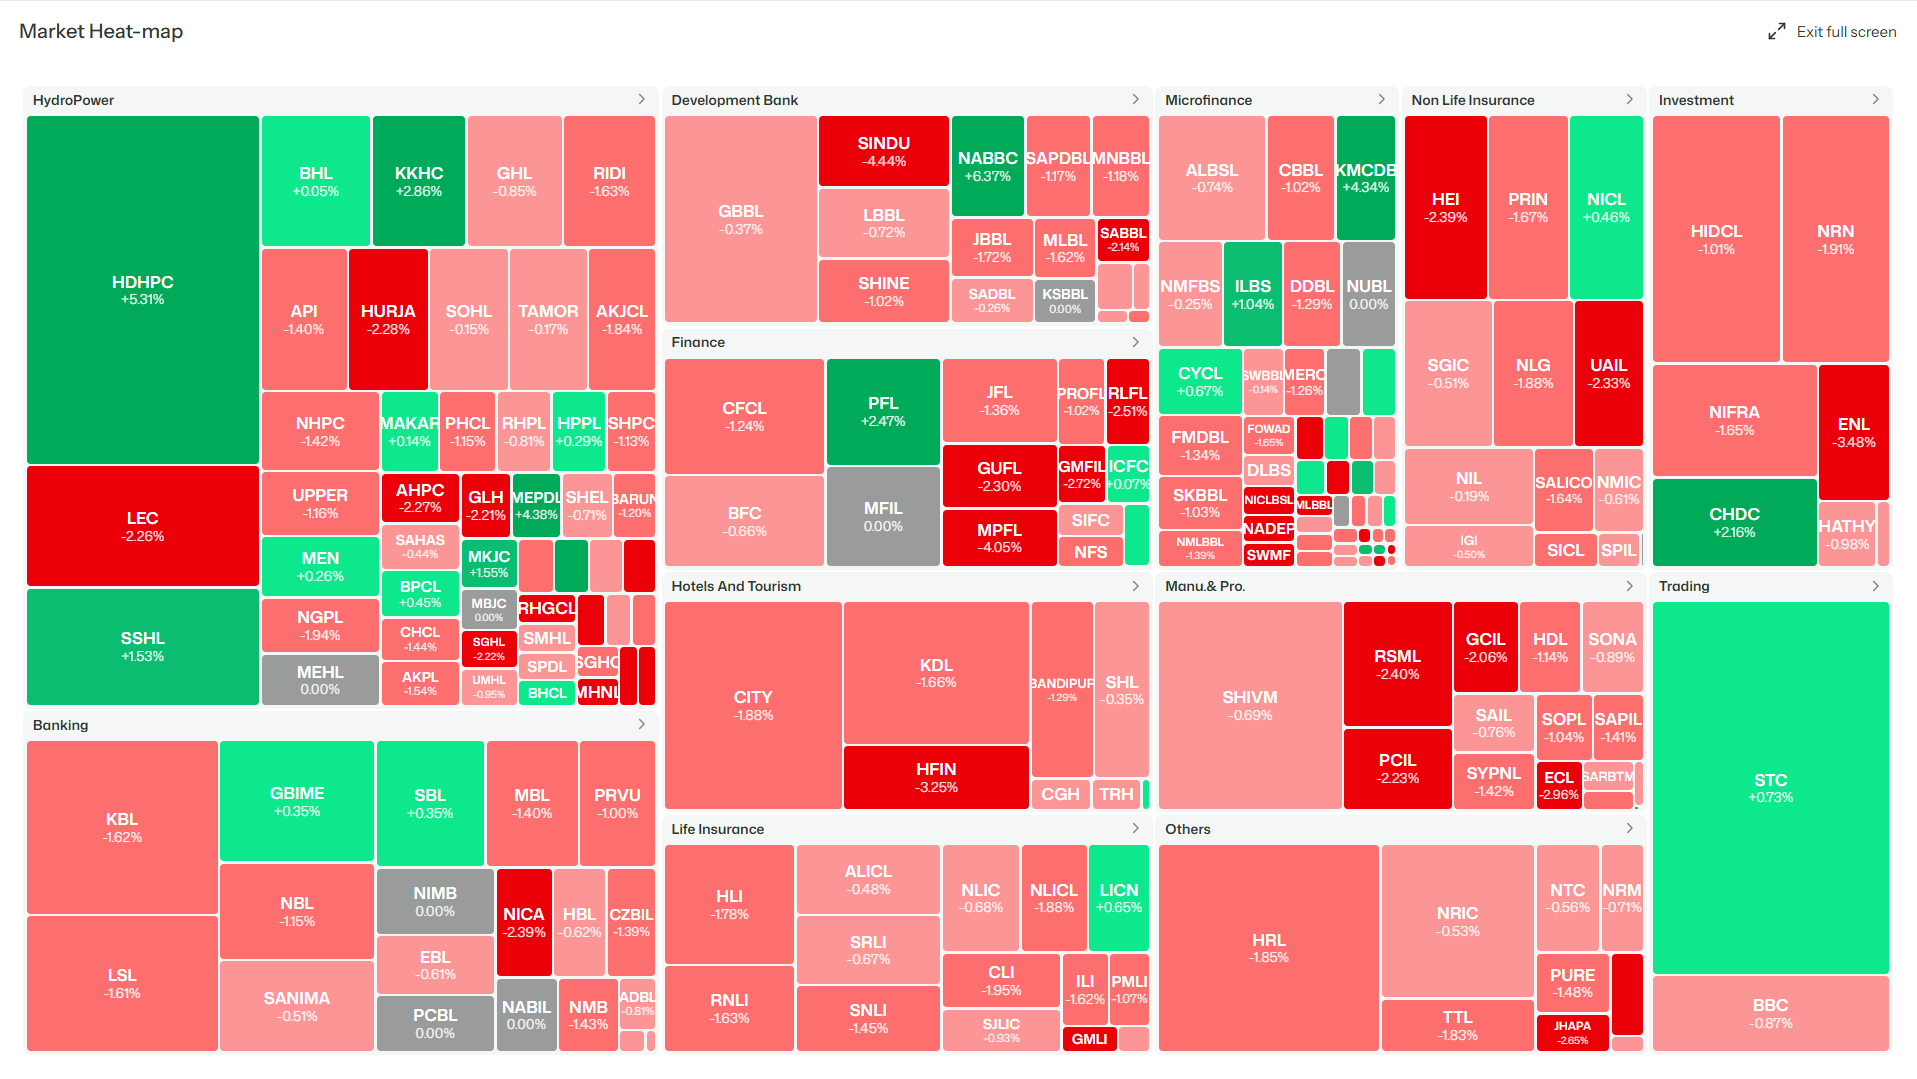
Eleven captured, all red, spread of 0.52 points between best and worst. This is indiscriminate selling, no sector rotation, no defensive bid.
Hydropower worst at −1.04% after leading yesterday at +1.84%. Both insurance sectors in the bottom three after leading yesterday. Manufacturing least-bad after being worst yesterday. Every sector did the opposite of what it did the session before.
Market Breadth
Metric | Count |
|---|---|
Advancers | 42 |
Decliners | 225 |
Unchanged | 15 |
Live universe | 282 |
A/D ratio | 0.19 |
A/D series (last nine captured sessions):
1.18 → 2.47 → 0.39 → 0.34 → 7.65 → [gap] → 22.08 → 0.19
225 decliners is the highest count of the coverage, beating the 200 on 10 September. The ratio of 0.19 is the third-lowest, behind only 0.08 (31 August) and 0.09 (28 August) from the capitulation lows.
The pattern this report has documented for a month held again, just at greater amplitude: extreme breadth readings do not persist. 7.65 gave way within two sessions. 22.08 gave way in one. Both of the last two records reversed immediately, and the reversal was proportional to the extreme.
Winners & Losers
Top Gainers
Stock | Sector | LTP | % |
|---|---|---|---|
NABBC | Development Bank | 745.00 | +6.37% |
HDHPC | HydroPower | 228.00 | +5.31% |
MEPDL | HydroPower | 703.00 | +4.38% |
KMCDB | Microfinance | 854.00 | +4.34% |
BNL | Manu. & Pro. | 14,000.00 | +3.59% |
UNL | Manu. & Pro. | 48,410.00 | +3.00% |
KKHC | HydroPower | 288.00 | +2.86% |
SNORL | HydroPower | 919.90 | +2.79% |
PFL | Finance | 373.00 | +2.47% |
CHDC | Investment | 2,368.00 | +2.16% |
HDHPC is the only gainer with real weight behind it, top of both activity tables, Rs 37.96 crore of turnover (7.0% of the entire market) and 16.64 lakh shares. On a day when 225 names fell, one stock absorbed one rupee in fourteen.
BNL and UNL were both in yesterday's loser table (−2.97% and −0.42%) and are in today's gainer table. Manufacturing was yesterday's worst sector and today's best. The churn is now mechanical.
PFL rose 2.47% on day two after listing following the PFL–SFCL merger, one of the few names building rather than reversing.
Top Losers
Stock | Sector | LTP | % |
|---|---|---|---|
RLEL | HydroPower | 784.90 | −5.21% |
NWCL | Others | 590.10 | −4.96% |
SMFBS | Microfinance | 1,375.00 | −4.58% |
SINDU | Development Bank | 430.00 | −4.44% |
MLBS | Microfinance | 1,020.00 | −4.32% |
SKHEL | HydroPower | 835.00 | −4.13% |
TSHL | HydroPower | 350.00 | −4.11% |
MPFL | Finance | 594.90 | −4.05% |
RHGCL | HydroPower | 264.00 | −4.00% |
MSHL | HydroPower | 538.00 | −3.93% |
Four of yesterday's top ten gainers are in today's top ten losers: SINDU (+11.03% → −4.44%), MPFL (+9.73% → −4.05%), RHGCL (+6.18% → −4.00%), MSHL (+6.67% → −3.93%).
SINDU's round trip is now complete and reversing. Three consecutive limit-downs to 359.70 on 10 September, a recovery to 450.00 yesterday and back to 430.00 today.
Six of the ten losers are hydropower, matching the sector's −1.04%.
Turnover & Volume Leaders
Most Active by Turnover
Stock | LTP | % | Turnover |
|---|---|---|---|
HDHPC | 228.00 | +5.31% | Rs 37.96 Cr |
RSML | 2,810.00 | −2.40% | Rs 25.10 Cr |
SHIVM | 676.30 | −0.69% | Rs 16.57 Cr |
SOHL | 653.00 | −0.15% | Rs 15.08 Cr |
LEC | 251.00 | −2.26% | Rs 14.68 Cr |
NRN | 1,439.90 | −1.91% | Rs 12.82 Cr |
SSHL | 212.00 | +1.53% | Rs 12.04 Cr |
TAMOR | 526.10 | −0.17% | Rs 12.02 Cr |
CHDC | 2,368.00 | +2.16% | Rs 11.48 Cr |
MEN | 652.70 | +0.26% | — |
Most Active by Volume
HDHPC (16.64 L, +5.31%), LEC (5.80 L, −2.26%), SSHL (5.62 L, +1.53%), KBL (3.99 L, −1.62%), LSL (3.14 L, −1.61%), BHL (2.96 L, +0.05%), KKHC (2.57 L, +2.86%), GHL (2.57 L, −0.85%), RIDI (2.53 L, −1.63%), API (−1.40%)
RSML fell 2.40% while taking second place by turnover at Rs 25.10 crore and printing three separate blocks worth Rs 3.68 crore. This is the fourth time in the coverage that RSML has combined heavy turnover, block activity and a falling price. When RSML's blocks appear alongside a red print, the stock has gone down the next session every time.
LEC fell 2.26% and slipped to fifth by turnover from first. The name that took 11.4% of the tape on 10 September is now a mid-table participant.
SSHL held at +1.53% with 5.62 lakh shares and Rs 12.04 crore, one of only two names with volume backing on the green side.
Signal Scorecard
Prior call | Status | What happened |
|---|---|---|
"Does 2,629–2,633 hold as support? Failing back below makes yesterday a blow-off into old resistance" | FAILED ON FIRST TEST | Closed 2,612.42, back under the zone. Yesterday's record gain was a blow-off into the band that broke on 18 August. |
"A/D at 22.08 must normalise; a snap back under 1.00 within two sessions would fit every prior breadth spike" | SNAPPED BACK IN ONE | 0.19. 225 decliners, the highest count of the coverage. |
"Turnover at Rs 8.29 arab is not a sustainable run-rate; a fall toward Rs 5 arab with the index rising would be healthy" | FELL, INDEX DIDN'T HOLD | Rs 5.39 arab with the index down 0.80%. The unhealthy version of the two scenarios. |
"Do blocks ever arrive?" | YES AND THEY SOLD | Top five at 1.72% of turnover up from 1.06%. MEN Rs 3.14 Cr, NRN Rs 2.45 Cr, RSML Rs 3.68 Cr across three. Institutional size returned on the down day. |
"An ICRA action on TVCL" (flagged since 3 Sep) | ARRIVED | Rs 8.2 billion of loans placed on negative watch over flash flood damage, fourteen days after the total-loss disclosure. The Myagdi template ran ten days; this ran fourteen. |
"The unresolved file, now fully unpriced" | ONE ITEM RE-PRICED | The TVCL rating action is the first of the flood threads to force itself back onto the tape. |
"Cash dividends 3 for 3; small dividends muted" | MORE DATA | ICRA Nepal 62.50%, Reliance Spinning 30% cash, Citizens Bank 4%, Kumari Bank 2.1053%. Reaction masked by a −0.80% tape; CZBIL closed −1.39%. |
"SEBON pre-disclosure: watch for the next one" | THIRD CASE | Kalinchowk Darshan (KDL) major shareholders filed to sell within three months. KDL closed −1.66%. |
Top Stories
1. The Cabinet taxes securities gains after the bell
The Cabinet, meeting at the Office of the Prime Minister and Council of Ministers, approved new advance tax rates on gains from the disposal of securities listed with SEBON, with the rate set by holding period. Government Spokesperson and Education Minister Sasmita Pokharel made it public on Wednesday; ShareSansar published at 5:59 PM.
Holding periodAdvance tax | |
|---|---|
More than 365 days (natural persons) | 3.5% |
365 days or less | 5.0% |
The tax will be collected by the entity performing the functions of the securities market that is deducted at source by NEPSE on disposal, not self-assessed.
Why it matters. Three things follow directly.
First, the structure penalises exactly the behaviour this market runs on. Twenty-five sessions of coverage have documented a tape where six of ten gainers become losers the next day, where no rotation held three sessions until RSML managed it once, and where names round-trip 25% inside a week. That is short-holding-period trading and it now carries a 5% levy at source versus 3.5% for holding past a year. A 150 basis point gap is not enormous, but it is the first structural incentive in this market to hold rather than churn.
Second, collection at source changes the cash-flow mechanics. Advance tax deducted by the exchange means the money leaves the account on sale rather than at assessment. For leveraged accounts and Rs 166.50 billion sits against share collateral, 72% of it in accounts above Rs 1 crore that tightens working capital on every round trip.
Third, and most immediately: the market fell before this was published. NEPSE closed at 3:00 PM down 21.19 points with 225 decliners. The announcement came at 5:59 PM. Either the decision circulated during the session or tomorrow opens with the news still unpriced. The honest position is that this report cannot tell which, and tomorrow's open is the test.
The same Cabinet meeting approved the Regulation on Simplification and Digitalisation of Government Decision-Making Procedures, 2083, the Cyclic Relief Fund Operation Procedure, 2083 several judicial and administrative promotions and power of attorney for a Saudi lawyer to handle insurance and compensation claims for Nepali citizens who died or were injured in Saudi Arabia.
2. TVCL: Rs 8.2 billion on negative watch, the call this report has been waiting on
ICRA has placed Trishuli Jal Vidyut's Rs 8.2 billion of loans on negative watch following flash flood damage.
This was flagged as overdue on 3 September, when TVCL disclosed to SEBON, NEPSE and CDSC that its 37 MW Upper Trishuli-3 'B' project at Sirupani, Kispang-5, Nuwakot was completely destroyed with the condition of most site employees unknown and no loss quantum given.
The template this report identified with Myagdi Hydropower has now run its full course a second time: damage → force majeure → unquantified insurance claim → debt servicing risk → rating action. Myagdi took roughly ten days from event to an [ICRANP-IR] B@ downgrade with explicit default-risk language. TVCL took fourteen days from disclosure to negative watch.
The number to hold onto is Rs 8.2 billion. That is the debt now formally under review against an asset that no longer exists. For scale, it is roughly a third of the entire Rs 25.87 billion of Bhotekoshi insurance claims filed across 583 parties from one project.
And it validates the arithmetic this report has carried for two weeks. Reconstruction cost is estimated near NPR 560 billion ($4 billion); hydro investment-value damage around NPR 180 billion; claims filed NPR 25.87 billion; and the Gen-Z settlement precedent ran at 32.4% (Rs 7.62 bn paid of Rs 23.53 bn). The gap between destroyed value and insured value was always going to land on lenders. TVCL is the first listed instance of it landing.
Watch next: Sagarmatha Jalabidhyut, which has sat on BBB- with Watch with Negative Implication since 9 September, and Niko Energy, carrying flagged construction and funding risk on its 9 MW Mathilo Bhurundi-A project.
Also from ICRA today: C.G. Motors assigned an A4 rating as revenue and margins decline.
3. NRB Act amendment clears the Finance Committee unanimously
The report on the Nepal Rastra Bank Act Amendment Bill was passed unanimously by the parliamentary Finance Committee.
Why it matters: five days ago Finance Minister Swarnim Wagle publicly assured that the government had not interfered with NRB's autonomy, a statement this report read as a response to pressure rather than an unprompted remark. The amendment bill clearing committee unanimously is the substance behind that statement. What the amendments actually contain will determine whether central bank independence is strengthened or quietly narrowed, and that detail is not yet public.
It also matters because this is the first piece of financial-sector legislation to make actual parliamentary progress during this coverage. The SEBON reform package announced on 7 September price discovery, qualified institutional investors, an SME board, Securities Act amendments still has no draft, no timeline and no bill. The NRB Act moved; the Securities Act has not.
Separately, NRB directed banks to ensure fair employee management after mergers and acquisitions, and Rastriya Banijya Bank extended corporate branch hours to 6 PM.
4. Deposit rates are still falling, the liquidity engine keeps running
Average bank interest rates declined again in Ashwin, with Prabhu leading deposit rates.
Why it matters: yesterday's report identified the liquidity surplus as the actual driver of this rally, repo at 4.25%, credit-to-deposit ratio around 74% against a 90% ceiling, average lending ~7%, deposits ~3.5%, one-year FD at the most competitive banks ~4.55%, savings 2.9%.
Rates falling further in Ashwin means the pressure pushing deposits toward equities is intensifying, not easing. That is the argument against reading today's −0.80% as the end of the move. The counter-argument arrived the same day in the form of a 5% advance tax on short-term gains which changes the after-tax return on exactly the trading behaviour that cheap deposits have been funding.
And gold rose Rs 1,700 per tola with silver up Rs 85. Bullion has been climbing throughout this coverage and now sits well above Rs 305,000. Deposits at 2.9%, equities newly taxed at 5% on short holdings, and gold rising, the competition for the marginal rupee just got more interesting.
5. Dividend season accelerates, and the numbers are getting large
Company | Dividend | Detail |
|---|---|---|
ICRA Nepal | 62.50% | 14th AGM called, the largest dividend of the coverage |
Reliance Spinning Mills | 30% cash | Book closure set, AGM Ashoj 22 |
Citizens Bank International (CZBIL) | 4% | FY2082/83 · stock −1.39% today |
Kumari Bank | 2.1053% cash | FY2082/83 |
Why it matters: this report's refined rule is that cash dividends move the tape and bonus-dominant ones do not, with the reaction scaling to size, GBIME's 6% cash produced +4.13%, GBBL's 20% produced a move to the top of the tape, KDL's 8.5%-bonus package produced −14.28%, and MBL's 6% produced only +0.80%.
Reliance Spinning's 30% cash is the second-largest cash payout announced in this coverage and the book closure is already set that is a hard date, not a proposal. ICRA Nepal's 62.50% is larger still though the company is a rating agency with a small float.
The clustering matters too. Four dividend announcements in one day, on top of Snow Rivers (10.5263%), Nabil Investment Banking (10% bonus + 11.05% cash, AGM Ashwin 20), GBIME (Ashwin 16) and KDL (Ashwin 16). The AGM calendar through Ashwin is now dense and the new 3.5% long-hold versus 5% short-hold tax gives holders a fresh reason to sit through book closure rather than trade around it.
6. Kalinchowk Darshan: the third pre-disclosure test
Major basic shareholders of Kalinchowk Darshan Limited have filed to sell shares within three months.
Why it matters: this is the third test of the SEBON rule requiring 5%-plus holders to notify before selling, and the scorecard so far is contradictory. UHEWA dampened, the stock closed +0.17% the session after its filing. ENL front-ran it closed limit-down two sessions before its six-holder filing was published, then limit-down again, a cumulative −27.7%, and now carries a 913,099-share overhang across seven holders.
KDL closed −1.66% today against a market down 0.80%. Mild underperformance, no collapse. KDL has now had a bad fortnight on its own account, it fell 14.28% on announcing a bonus-heavy 8.9474% dividend and now its major shareholders are exiting. Its AGM is Ashwin 16.
7. SEBON lets capital market firms fund disaster relief from CSR
SEBON has allowed capital market firms to use their CSR funds for disaster relief.
A small measure with a sensible read-across: it channels an existing mandatory spending pool toward the flood response without new appropriation. Corporate relief contributions have been running steadily MV Dugar Group Rs 1.11 crore, Mobile Phone Importers Association Rs 31 lakh, Delhi Mahal Group Rs 11 lakh, alongside NRB's Rs 1.39 crore, the Nepali Congress Rs 10 million and the ADB's $5 million grant. Against a reconstruction estimate near NPR 560 billion, all of it together is a rounding error which is the point worth keeping in view.
8. Fuel prices held, and the rest of the board
Nepal Oil Corporation kept fuel prices unchanged despite higher IOC rates absorbing the increase rather than passing it through, which protects festival-quarter inflation but transfers the cost to NOC's own book.
Corporate and governance: Unilever Nepal (UNL) director Ravishankar A. resigned from the board, the stock closed +3.00%, one of the day's better performers. Mandu Hydropower re-appointed Ravindra Lal Shrestha as Chairman. Min Bahadur Bohara was appointed CEO of Nerude Mirmire Laghubitta.
Policy and politics: President Paudel signed the bill restoring provisions of the Nepal Special Service Act. The government proposed six-month paid maternity leave and 42-day paternity care leave, a material change to employer cost structures if enacted. US diplomat Megan Bouldin met PM Balendra Shah, days after his meeting with business leaders on investment and ahead of his UN General Assembly trip.
Corporate Actions & Events
Company | Action | Detail |
|---|---|---|
Government / Cabinet | Tax | Advance tax on securities gains: 5% if held ≤365 days, 3.5% if >365 days; collected at source by NEPSE |
Trishuli Jal Vidyut (TVCL) | Rating | Rs 8.2 bn loans placed on NEGATIVE WATCH, flash flood damage |
C.G. Motors | Rating | A4 assigned; revenue and margins declining |
ICRA Nepal | Dividend | 62.50% proposed, 14th AGM called |
Reliance Spinning Mills | Dividend | 30% cash · book closure set, AGM Ashoj 22 |
Citizens Bank International (CZBIL) | Dividend | 4% proposed, FY2082/83 |
Kumari Bank | Dividend | 2.1053% cash, FY2082/83 |
Snow Rivers | Dividend | 10.5263% · 5th AGM |
Nabil Investment Banking | Dividend | 10% bonus + 11.05% cash, AGM Ashwin 20 |
Global IME Bank (GBIME) | Dividend | 10% (4% bonus + 6% cash), AGM Ashwin 16 |
Kalinchowk Darshan (KDL) | Shareholder sales | Major basic shareholders to sell within three months, AGM Ashwin 16 |
Emerging Nepal (ENL) | Shareholder sales | 7 holders, 913,099 shares, 3-month window |
NRB Act Amendment Bill | Legislation | Report passed unanimously by Finance Committee |
SEBON | Regulation | Capital market firms may use CSR funds for disaster relief |
NRB | Directive | Banks to ensure fair employee management post-M&A |
Unilever Nepal (UNL) | Board | Director Ravishankar A. resigned |
Mandu Hydropower | Board | Ravindra Lal Shrestha re-appointed Chairman |
Nerude Mirmire Laghubitta | Management | Min Bahadur Bohara appointed CEO |
Pokhara Finance (PFL) | Listing | Merger shares listed 15 Sep · +2.47% day two |
Sagarmatha Jalabidhyut | Rating | BBB-, Watch with Negative Implication |
Himalayan Reinsurance (HRL) | Board | Chair still vacant |
Shikhar Power Development | Lock-in expiry | 1.11 lakh units, Ashwin 2, 2083 |
What to Watch
1. Does the tax get priced tomorrow, or was it priced today? The Cabinet decision published at 5:59 PM nearly three hours after a 21-point decline on 225 decliners. If tomorrow opens sharply lower, today's selling was anticipation and the news is still working through. If tomorrow opens flat or higher, today was profit-taking and the market has decided a 5%/3.5% advance tax is survivable. This is the cleanest binary the coverage has offered.
2. The 5% versus 3.5% spread, over weeks not days. A 150 basis point penalty on short holdings is a structural nudge toward holding past 365 days. Watch whether turnover settles at a lower run-rate and whether the one-session churn pattern, six of ten gainers becoming losers starts to break down. That pattern has been the single most reliable feature of this market; the tax is the first thing that directly attacks it.
3. 2,600, then 2,594. Twelve points and eighteen points below. 2,594 was the 27 August close and is the first genuinely tested level underneath. Above, the 2,629–2,633 zone now needs to be cleared on a second attempt and second attempts at rejected resistance usually need fresh news.
4. TVCL, and who follows. Rs 8.2 billion on negative watch is the first flood loss to become a formal credit event at a listed company. Sagarmatha Jalabidhyut has sat on Watch with Negative Implication since 9 September; Niko Energy carries flagged construction and funding risk. Watch for a second name and watch whether any bank discloses exposure to TVCL's Rs 8.2 billion.
5. Block direction. Blocks returned today at 1.72% of turnover: MEN Rs 3.14 Cr flat, NRN Rs 2.45 Cr down 1.91%, RSML Rs 3.68 Cr down 2.40%. Two of three came with falling prices. If tomorrow brings more blocks on red prints, larger holders are exiting into the tax change.
6. The AGM calendar against the new tax. Reliance Spinning's 30% cash book closure is set; Ashwin 16 has both GBIME and KDL; Nabil Investment Banking is Ashwin 20. With short-term gains now taxed 150bp higher than long-term, watch whether holders sit through book closures instead of trading around them that would show up as thinner turnover on dividend names in the days either side.
7. Deposit rates versus the tax. Rates fell again in Ashwin which pushes more deposits toward equities. The tax pulls the other way. Gold is up Rs 1,700 a tola. Whichever of these three dominates over the next fortnight determines whether the liquidity rally resumes or this was the top.
Disclaimer
This report has been prepared by Nepalytix for informational and educational purposes only and does not constitute investment advice, an offer, or a solicitation to buy or sell any securities.
The information contained in this report is based on sources believed to be reliable; however, Nepalytix does not guarantee its accuracy, completeness, or timeliness. Opinions, estimates, and projections expressed herein are those of the authors as of the date of publication and are subject to change without notice.
Investing in securities involves risks, including the possible loss of principal. Past performance is not indicative of future results. Readers are advised to conduct their own independent research and consult with a qualified financial advisor before making any investment decisions.
Nepalytix and its contributors may hold positions in the securities discussed in this report at the time of publication or thereafter.
Neither Nepalytix nor any of its affiliates accept any liability for any loss arising from the use of this report or its contents.