NEPSE Surges 49 Points as Rs 8.29 Arab Floods Into the Market
NEPSE surged 48.57 points to 2,633.62 on record turnover, overwhelming breadth and the first bullish technical majority of the coverage.
Markets Today
The 30-Second Read
NEPSE closed 2,633.62, up 48.57 (+1.87%), the largest single-day gain of the coverage through 2,594, through 2,600, and straight into the old 2,629–2,633 zone that held four tests before breaking on 18 August. The entire drawdown is almost gone: the index is 16.46 points, or 0.62% below where this coverage began on 7 August.
Turnover Rs 8.29 arab 74% above the previous coverage high of Rs 4.77 arab. Transactions 78,869 up 57% on the old record. Volume 2.04 crore.
A/D 22.08. 265 advancers, 12 decliners. The record three sessions ago was 7.65; before that, 2.57.
The technical scan inverted. Bullish 36.07% against bearish 22.17%, the first time in the entire coverage that bullish signals have outnumbered bearish. Prior bullish high was 25.45%.
Average deal size hit Rs 1.05 lakh, a coverage record but the top five blocks totalled only Rs 8.80 crore, 1.06% of turnover. Big tickets everywhere, almost no block placements. This is broad money, not a few large hands.
ShareSansar published the explanation the same day: repo at 4.25%, credit-to-deposit ratio at ~74% against a 90% ceiling, one-year FD at ~4.55%, savings at 2.9%. Idle deposits have nowhere to go.
Coverage gap: this report has no terminal capture for 13 and 14 September. Today's +48.57 implies a prior close of 2,585.05, so the index gained 25.56 points across those two sessions. Series and streak counts are marked accordingly.
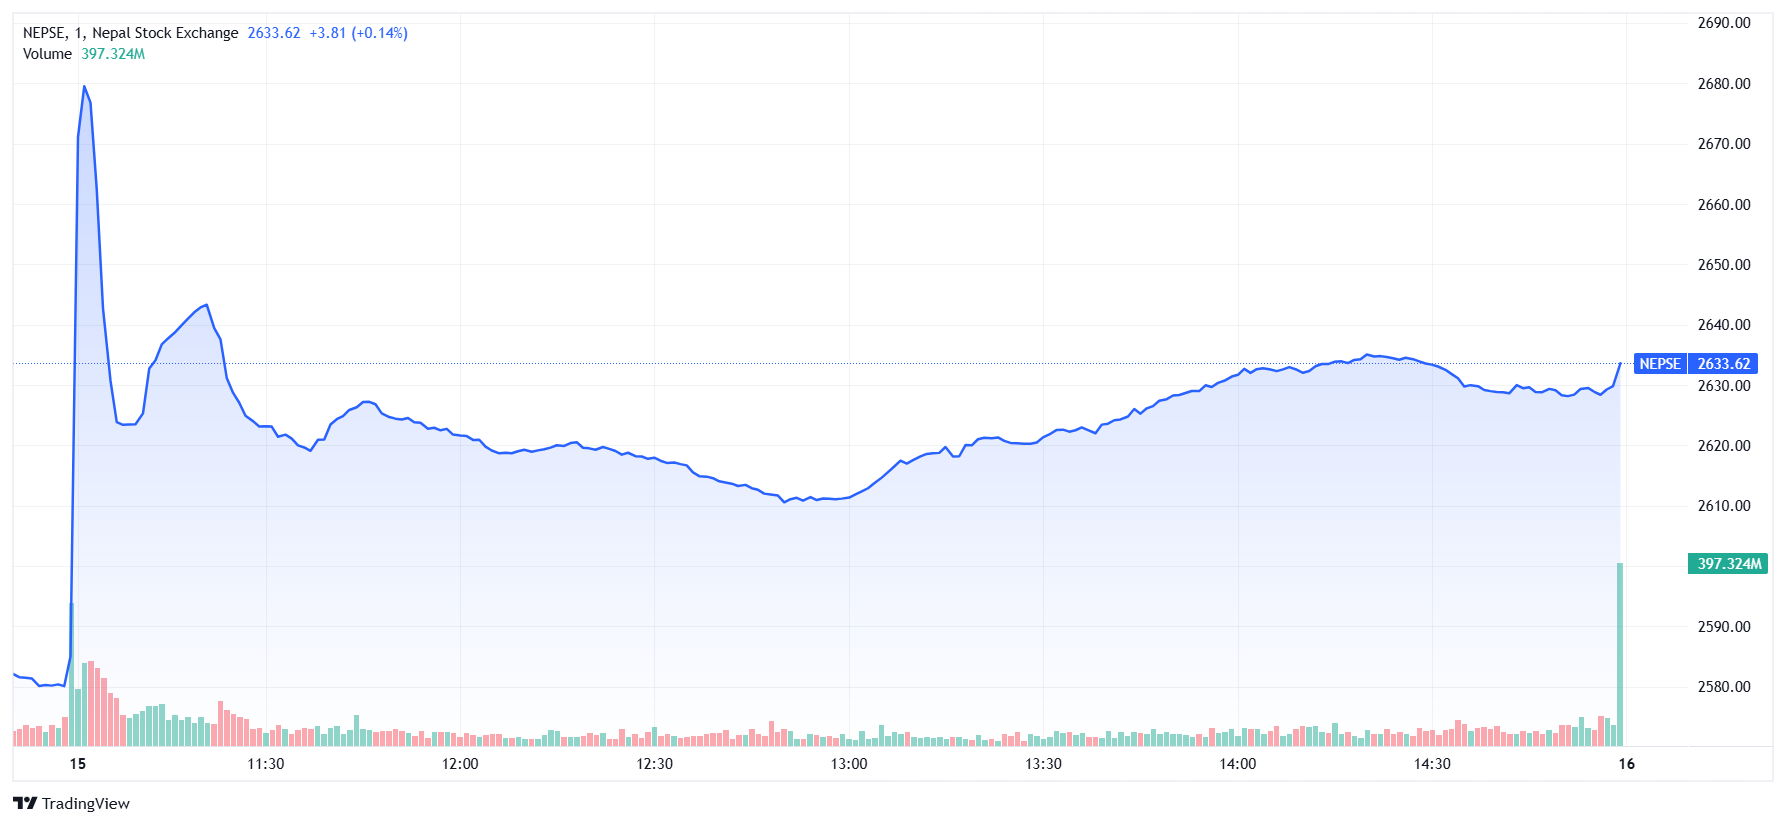
For twenty-odd sessions this report documented a market that could not hold a direction three days, priced headlines for one session and failed fifteen rotations in a row. That market is gone, and it went in about a week.
NEPSE closed 2,633.62, up 48.57 points (+1.87%), on Rs 8.29 arab, 2.04 crore units and 78,869 transactions across 347 scrips. Advancers 265, decliners 12, unchanged 5 an A/D of 22.08.
Take the turnover seriously. Rs 8.29 arab is not a new high by a margin, it is nearly double the old one. The coverage range was Rs 2.91 to Rs 4.77 arab; today printed 74% above the top of it. Transactions at 78,869 against a previous record of 50,844 say the same thing from the other direction: far more people traded, and they traded far more money.
The scan inverted, and that is the single most significant number on the page. Bullish signals reached 36.07% against bearish at 22.17%. Across every prior session in this dataset bearish outnumbered bullish, usually by 1.5 to 2 times and the bullish reading never once cleared 25.45%. Today it cleared 36%. Total signals also jumped to 3,970, meaning more names are generating any signal at all.
Large caps led. Sensitive +2.00% and Float +2.00% against NEPSE's +1.87%. The quality end outperformed on the biggest up-day of the coverage which is what a genuine re-rating looks like rather than a small-cap squeeze.
Only twelve names fell, and the worst was down 2.97%. Four of the ten in the loser table are Manufacturing which is why Manu & Pro was the weakest sector at +0.77%.
The one thing that has not changed: institutional block flow is still absent. The top five blocks totalled Rs 8.80 crore, 1.06% of turnover, the lowest share of the coverage. The largest was LEC at Rs 2.12 crore. Meanwhile average deal size hit a record Rs 1.05 lakh. Read those two together: ticket sizes are large across the whole tape but nobody is placing size through the block window. This is a broad-based bid not a handful of institutions accumulating.
Which is exactly what the liquidity thesis predicts. With a one-year fixed deposit paying 4.55% and a savings account 2.9%, the marginal rupee in the banking system has no competitive home. The market is absorbing deposits, not discovering value.
Index Snapshot
Index | Close | % |
|---|---|---|
NEPSE | 2,633.62 | +1.87% |
Sensitive | 467.45 | +2.00% |
Float | 181.13 | +2.00% |
Turnover Rs 8.29 arab
Volume 2.04 crore units
Transactions 78,869
Scrips traded 347
Sectoral Indices Performance
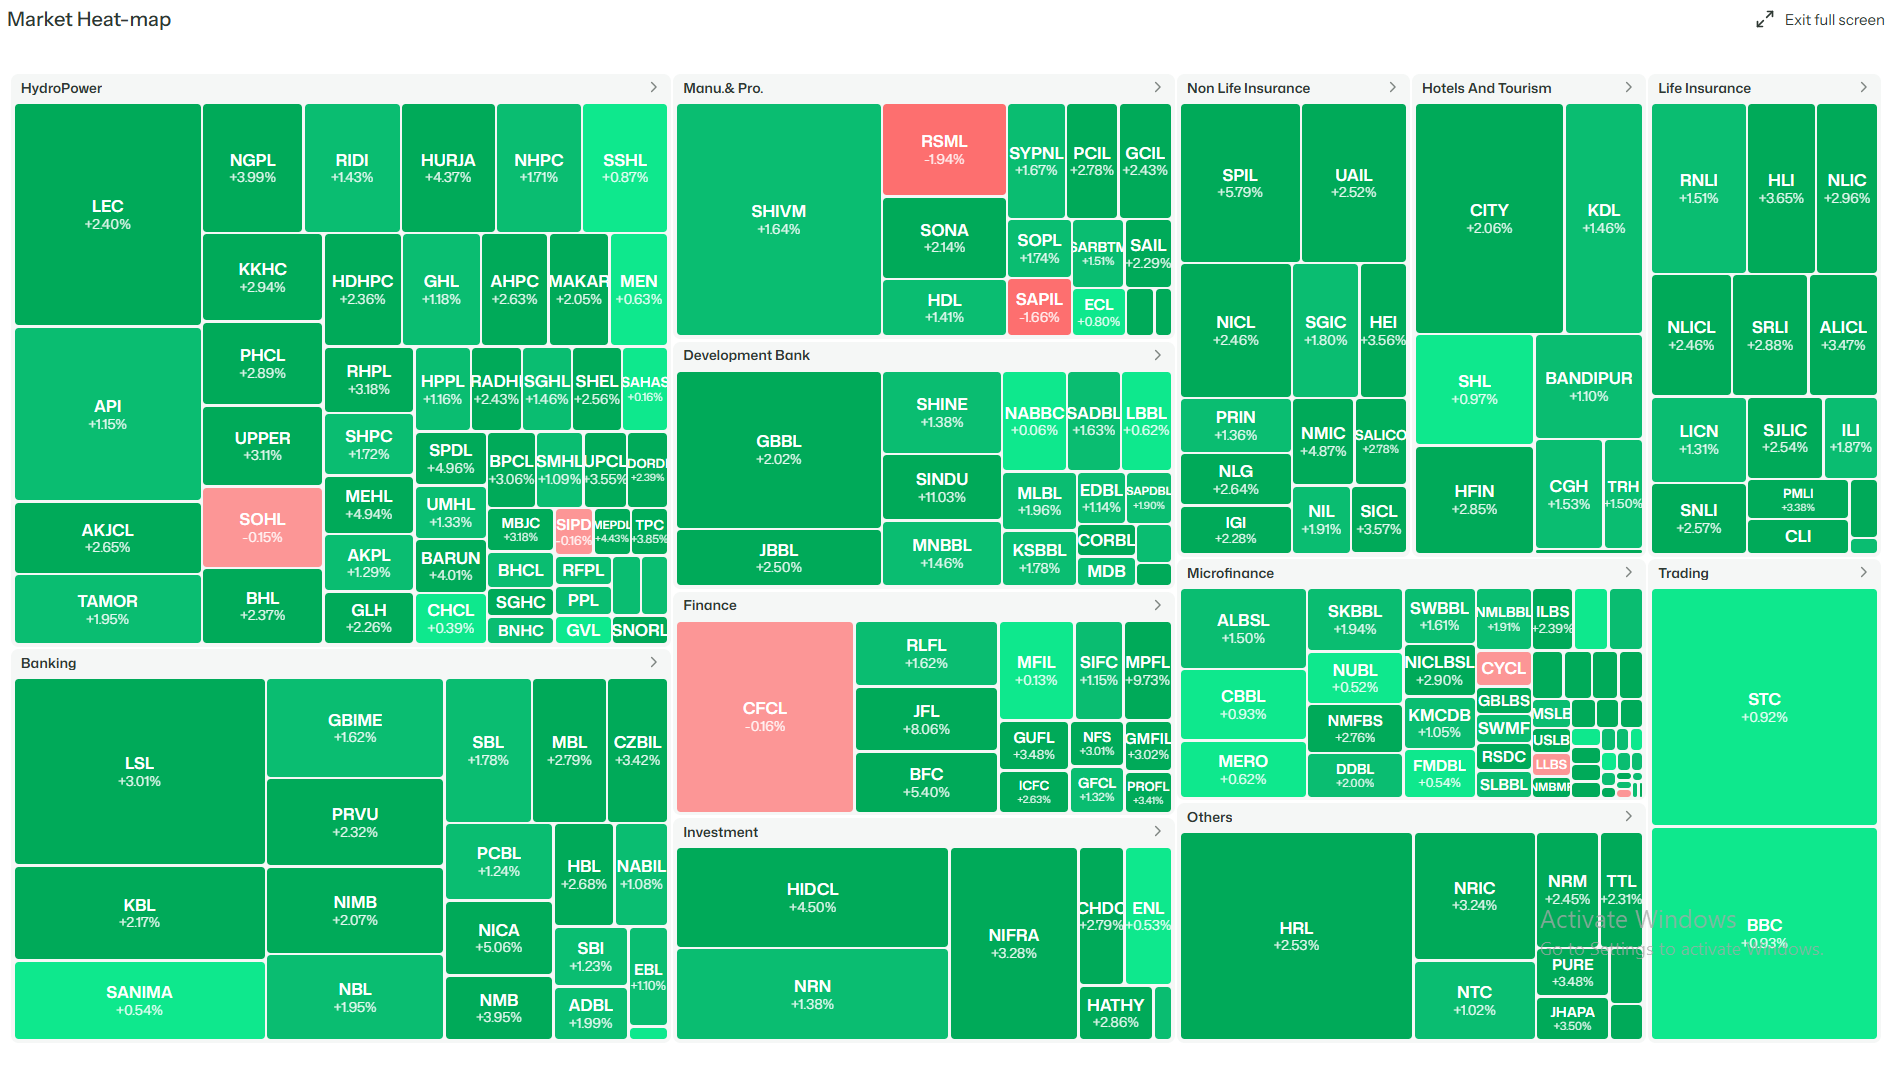
Twelve captured, all green, and the spread is narrow 2.05 points between best and worst. Nothing is being singled out; everything is being bought.
Both insurance sectors lead. Non-Life at +2.82% is the same sector that fell 1.57% on the Gen-Z settlement data six sessions ago. SPIL +5.79%, NMIC +4.87%, SALICO +2.78%, NLG +2.64%, UAIL +2.52%, NICL +2.46%. The flood-claim overhang has stopped mattering to price.
Market Breadth
Metric | Count |
|---|---|
Advancers | 265 |
Decliners | 12 |
Unchanged | 5 |
Live universe | 282 |
A/D ratio | 22.08 |
A/D series (last eight captured sessions): 2.15 → 2.57 → 1.18 → 2.47 → 0.39 → 0.34 → 7.65 → [gap] → 22.08
94% of the quoted universe advanced. Twelve names fell out of 282. The prior record of 7.65 was itself three times the record before it — the ratio has gone from 0.34 to 22.08 in five captured sessions.
The standing caution applies with more force, not less: readings this extreme are not sustainable and have historically marked exhaustion as often as breakout. But the honest counter is that this is now supported by turnover 74% above the old high and a scan that has inverted for the first time. Extreme breadth on record money is a different animal from extreme breadth on thin money which is what 11 September was.
Winners & Losers
Top Gainers
Stock | Sector | LTP | % |
|---|---|---|---|
DLBS | Microfinance | 1,119.00 | +14.96% |
SINDU | Development Bank | 450.00 | +11.03% |
MPFL | Finance | 620.00 | +9.73% |
JFL | Finance | 295.00 | +8.06% |
MSHL | HydroPower | 560.00 | +6.67% |
JOSHI | HydroPower | 271.80 | +6.13% |
TVCL | HydroPower | 317.60 | +5.87% |
SPIL | Non Life Insurance | 639.00 | +5.79% |
BFC | Finance | 470.10 | +5.40% |
IHL | HydroPower | 326.50 | +5.32% |
SINDU has completed a full round trip. Three consecutive limit-downs took it from 585.50 to 359.70 on 10 September; it is now back to 450.00, up 25.1% from the low in four sessions. Whatever forced that selling is finished.
MPFL +9.73% was the worst loser on 11 September at −5.71%. JFL and BFC join it — three of the top ten gainers are Finance, the sector that has been dragged all week by single-stock collapses.
TVCL +5.87% is the name that disclosed the total loss of the 37 MW Upper Trishuli-3 'B'. It fell 11.2% across two sessions when the tape finally priced the disclosure; it is now at 317.60, essentially back to where it sat before the reaction. Still no ICRA action.
Top Losers
Stock | Sector | LTP | % |
|---|---|---|---|
BNL | Manu. & Pro. | 13,515.00 | −2.97% |
RSML | Manu. & Pro. | 2,879.00 | −1.94% |
SAPIL | Manu. & Pro. | 1,420.00 | −1.66% |
SPL | HydroPower | 624.20 | −1.12% |
CYCL | Microfinance | 1,490.00 | −0.67% |
UNL | Manu. & Pro. | 47,000.00 | −0.42% |
MANDU | HydroPower | 697.00 | −0.40% |
LLBS | Microfinance | 860.00 | −0.35% |
JSLBB | Microfinance | 969.90 | −0.22% |
CFCL | Finance | 573.00 | −0.16% |
This is the shallowest loser table recorded here by a wide margin. Only twelve names fell in the entire market, seven of these ten by less than 1.2%, and the whole list barely constitutes selling.
RSML fell 1.94% while topping the turnover table at Rs 32.70 crore. It also took a Rs 1.45 crore block. Heavy money, negative direction, the same pattern that ended its three-day streak on 10 September.
Turnover & Volume Leaders
Most Active by Turnover
Stock | LTP | % | Turnover |
|---|---|---|---|
RSML | 2,879.00 | −1.94% | Rs 32.70 Cr |
SHIVM | 681.00 | +1.64% | Rs 31.57 Cr |
API | 343.90 | +1.15% | Rs 28.44 Cr |
NRN | 1,468.00 | +1.38% | Rs 28.30 Cr |
LEC | 256.00 | +2.40% | Rs 27.33 Cr |
LSL | 236.30 | +3.01% | Rs 19.56 Cr |
TAMOR | 527.00 | +1.95% | Rs 17.42 Cr |
SOHL | 654.00 | −0.15% | Rs 16.22 Cr |
NGPL | 417.00 | +3.99% | Rs 13.71 Cr |
GBBL | 455.00 | +2.02% | — |
Most Active by Volume
LEC (10.63 L), LSL (8.38 L), API (8.26 L), SHIVM (4.63 L), KBL (4.28 L, +2.17%), SANIMA (3.57 L), AKJCL (3.46 L, +2.65%), TAMOR (3.32 L), NGPL (3.32 L), RIDI (+1.43%)
Concentration has broken down, which is healthy. On 10 September LEC alone was 11.4% of turnover and the top four were 25.6%. Today the largest single name is RSML at 3.9%, and the top five are roughly 18% of a far bigger pie. Money is spread across the tape rather than piled into one name.
LSL is new and worth watching: Rs 19.56 crore, 8.38 lakh shares, +3.01% and it took a Rs 1.13 crore block plus the third and fourth largest quantity prints. A banking name arriving in both tables with block support on the biggest day of the coverage.
Three banks in the volume table (LSL, KBL, SANIMA), consistent with Banking at +1.90% and Sensitive outperforming.
Signal Scorecard
Prior call | Status | What happened |
|---|---|---|
"2,560.84 is 1.35 points away; open space to 2,594.27" | CLEARED AND THEN SOME | Closed 2,633.62 through 2,594, through 2,600, into the old 2,629–2,633 zone. Coverage drawdown reduced to −0.62%. |
"Does A/D print above 1.00?" | 22.08 | 265 advancers, 12 decliners. Third consecutive record in five captured sessions. |
"Do the blocks come back?" | NO | Top five = 1.06% of turnover, lowest share of the coverage. This rally has no institutional block footprint at all yet average deal size set a record. Broad money, not concentrated money. |
"LEC on day three" | UNVERIFIABLE (gap) | +2.40% today at 256.00, still top by volume, and took the two largest blocks. Alive but 13–14 September are not captured. |
"Reform text, or the absence of it" | STILL ABSENT AND IT DIDN'T MATTER | No draft amendment, no QII consultation. The driver turned out to be liquidity, not policy. The 7 September reform rally is now clearly the wrong explanation for what followed. |
"ENL's overhang against every bounce" | EASING | ENL +0.53% barely participating on a day 94% of the market rose. 913,099 shares still pending. Underperformance in a melt-up is its own signal. |
"SINDU on day four" | FULL ROUND TRIP | +11.03% to 450.00, up 25.1% from the 359.70 low. |
"The technical scan, demoted 10 Sep" | INVERTED | 36.07% bullish vs 22.17% bearish first bullish majority of the coverage. Confirming rather than diverging. |
Top Stories
1. The actual explanation: Nepal has too much money and nowhere to put it
ShareSansar published the piece that makes sense of the last week, on the day the market added 48.57 points on Rs 8.29 arab.
The numbers: NRB's policy repo rate sits at 4.25%. The credit-to-deposit ratio is around 74% against a 90% regulatory ceiling, banks have substantial room to lend and loan demand is not arriving fast enough to use it. Average lending rate is roughly 7%, deposit rate near 3.5%, one of the thinnest spreads in years. A one-year fixed deposit at the most competitive banks pays about 4.55%; a savings account, 2.9%.
The argument is straightforward and this report's data supports it directly. When deposits barely beat inflation, money migrates into real estate, and into shares. NRB separately reported real estate transactions up 4.74% in FY2082/83 which is the same money moving.
Why this reframes the coverage. The 7 September reform announcement was treated here as the first macro catalyst to move the index. It looks now like a trigger rather than a cause. The reform rally reversed within a session and what followed four days of accelerating gains culminating in nearly double the previous record turnover is not the profile of a policy trade. It is the profile of a deposit base finding a destination.
The article's three cautions are worth restating because they are testable: don't mistake liquidity for conviction, since a rally built on cheap deposit alternatives reverses when rates normalise or government securities absorb bank liquidity; separate sentiment sectors from earnings sectors; and watch the CD ratio rather than the index as long as it sits well below 90%, equities remain the default home for idle cash, which cuts both ways.
One corroborating detail: FDI stock has crossed Rs 340 billion, which is patient capital entering the real economy and a genuinely different signal from daily NEPSE flow.
The uncomfortable implication. This market has now recovered essentially its entire drawdown down just 0.62% from 7 August without resolving a single one of the threads this report has tracked. No restoration timeline for RHPL, CHCL or the Trishuli-3 'B' substation. No ICRA action on TVCL. NPR 560 billion of reconstruction cost unfunded. Rs 154 billion of flood damage uninsured. HRL's chair still vacant. Rs 166.50 billion of margin lending outstanding. No NRB circular on flood-affected loan classification. None of that has improved. The price has.
2. India approves 654 MW to Nepal, 18 hours daily
India has approved power supply of up to 654 MW to Nepal for 18 hours a day.
Why it matters: this is the direct fix for the flood's generation shortfall. Twelve projects went offline and exports fell from roughly 1,000 MW to 650 MW. Import capacity of this size stabilises domestic supply and removes load-shedding risk through the festival quarter but it also reverses the trade flow. Nepal ran a roughly NPR 19.97 billion net electricity trade surplus in FY2082/83; large-scale imports erode it, and they land on NEA, already reporting a 43% profit decline and the offtaker for essentially every listed hydro PPA.
Hydropower closed +1.84% on the news of importing power. That tells you what kind of market this is right now.
3. NRB: fintech strategy, and Rs 100 notes at ATMs
NRB unveiled a five-year fintech strategy to drive digital finance and innovation and directed commercial banks to make Rs 100 notes available at ATMs.
Why it matters: the fintech strategy is structural and slow-burning. The ATM directive is the one that touches the flood story, small-denomination cash availability matters in disrupted districts, following NRB's earlier directive to maintain banking services in flood-affected areas. Still nothing on loan classification or provisioning relief for flood-hit borrowers.
4. Corporate flow
Pokhara Finance (PFL) shares listed on NEPSE following its merger with SFCL, new supply in a Finance sector that closed +2.23%. Snow Rivers Limited proposed a 10.5263% dividend and called its 5th AGM. Relief contributions continued from Delhi Mahal Group (Rs 11 lakh).
Corporate Actions & Events
Company | Action | Detail |
|---|---|---|
Snow Rivers | Dividend | 10.5263% proposed, 5th AGM called |
Pokhara Finance (PFL) | Merger listing | Shares listed post PFL–SFCL merger |
Machhapuchchhre Bank (MBL) | Dividend | 6% proposed, +2.79% today |
Nabil Investment Banking | AGM + dividend | 10% bonus + 11.05% cash, Ashwin 20 |
Global IME Bank (GBIME) | AGM + dividend | 10% (4% bonus + 6% cash), Ashwin 16 |
Kalinchowk Darshan (KDL) | AGM + book closure | 8.9474% (8.5% bonus), Ashwin 16 |
Garima Bikas Bank (GBBL) | Dividend | 20% proposed |
Everest Bank (EBL) | Book closure | 15% dividend |
Emerging Nepal (ENL) | Shareholder sales | 7 holders, 913,099 shares, 3-month window |
Trishuli Jal Vidyut (TVCL) | Disclosure | UT-3 'B' total loss , no rating action yet |
Sagarmatha Jalabidhyut | Rating | BBB-, Watch with Negative Implication |
Himalayan Reinsurance (HRL) | Board | Chair still vacant ,+2.53% today |
Shikhar Power Development | Lock-in expiry | 1.11 lakh units · Ashwin 2, 2083 |
Saurya Krishi + two investment cos. | IPO | In SEBON pipeline |
What to Watch
1. Does 2,629–2,633 hold as support? It held four tests as support before breaking, which makes it meaningful. Closing above it for a second session converts the level and opens the path to 2,650.08. Failing back below it makes today a blow-off into old resistance, the classic place for a melt-up to end.
2. The CD ratio, not the index. The liquidity thesis is testable. As long as credit-to-deposit sits near 74% against a 90% ceiling and FD rates stay near 4.55%, the deposit base keeps arriving. The signals that would end it: NRB normalising rates, a large government securities issue absorbing bank liquidity, or loan demand recovering. NRB is already withdrawing Rs 85 billion from BFIs, watch whether that continues or accelerates.
3. Turnover at Rs 8.29 arab is not a sustainable run-rate. The coverage average is roughly Rs 3.7 arab. A fall back toward Rs 5 arab with the index still rising would be healthy; a fall toward Rs 4 arab with the index flat would say the surge was a single day of capitulation buying.
4. A/D at 22.08 must normalise. Twelve decliners out of 282 cannot repeat. The constructive outcome is a rise in decliner count toward 60–100 while the index holds that would be rotation inside an uptrend. A snap back under 1.00 within two sessions would fit every prior breadth spike in this dataset.
5. Do blocks ever arrive? Five sessions of rally with block flow at 1.06% of turnover. If institutions are going to participate, the block tape is where it shows first. Their continued absence is the strongest argument that this is a retail liquidity move that reverses when deposit economics change.
6. The unresolved file, now fully unpriced. TVCL up 5.87% with no rating action. Non-Life leading at +2.82% against a 32.4% settlement precedent. Hydro up on news of importing power. The market has repriced away every risk in this report without any of them being resolved. The specific catalysts that could force re-engagement: an ICRA action on TVCL, an NRB circular on flood-affected loans, or a reconstruction financing plan for the NPR 560 billion.
Disclaimer
This report has been prepared by Nepalytix for informational and educational purposes only and does not constitute investment advice, an offer, or a solicitation to buy or sell any securities.
The information contained in this report is based on sources believed to be reliable; however, Nepalytix does not guarantee its accuracy, completeness, or timeliness. Opinions, estimates, and projections expressed herein are those of the authors as of the date of publication and are subject to change without notice.
Investing in securities involves risks, including the possible loss of principal. Past performance is not indicative of future results. Readers are advised to conduct their own independent research and consult with a qualified financial advisor before making any investment decisions.
Nepalytix and its contributors may hold positions in the securities discussed in this report at the time of publication or thereafter.
Neither Nepalytix nor any of its affiliates accept any liability for any loss arising from the use of this report or its contents.