NEPSE’s Recovery Breaks on Heavy Selling
NEPSE fell 36.25 points after briefly clearing 2,650 with 253 stocks declining and volume reaching a record 2.16 crore units as selling spread across the market.
Markets Today
The 30-Second Read
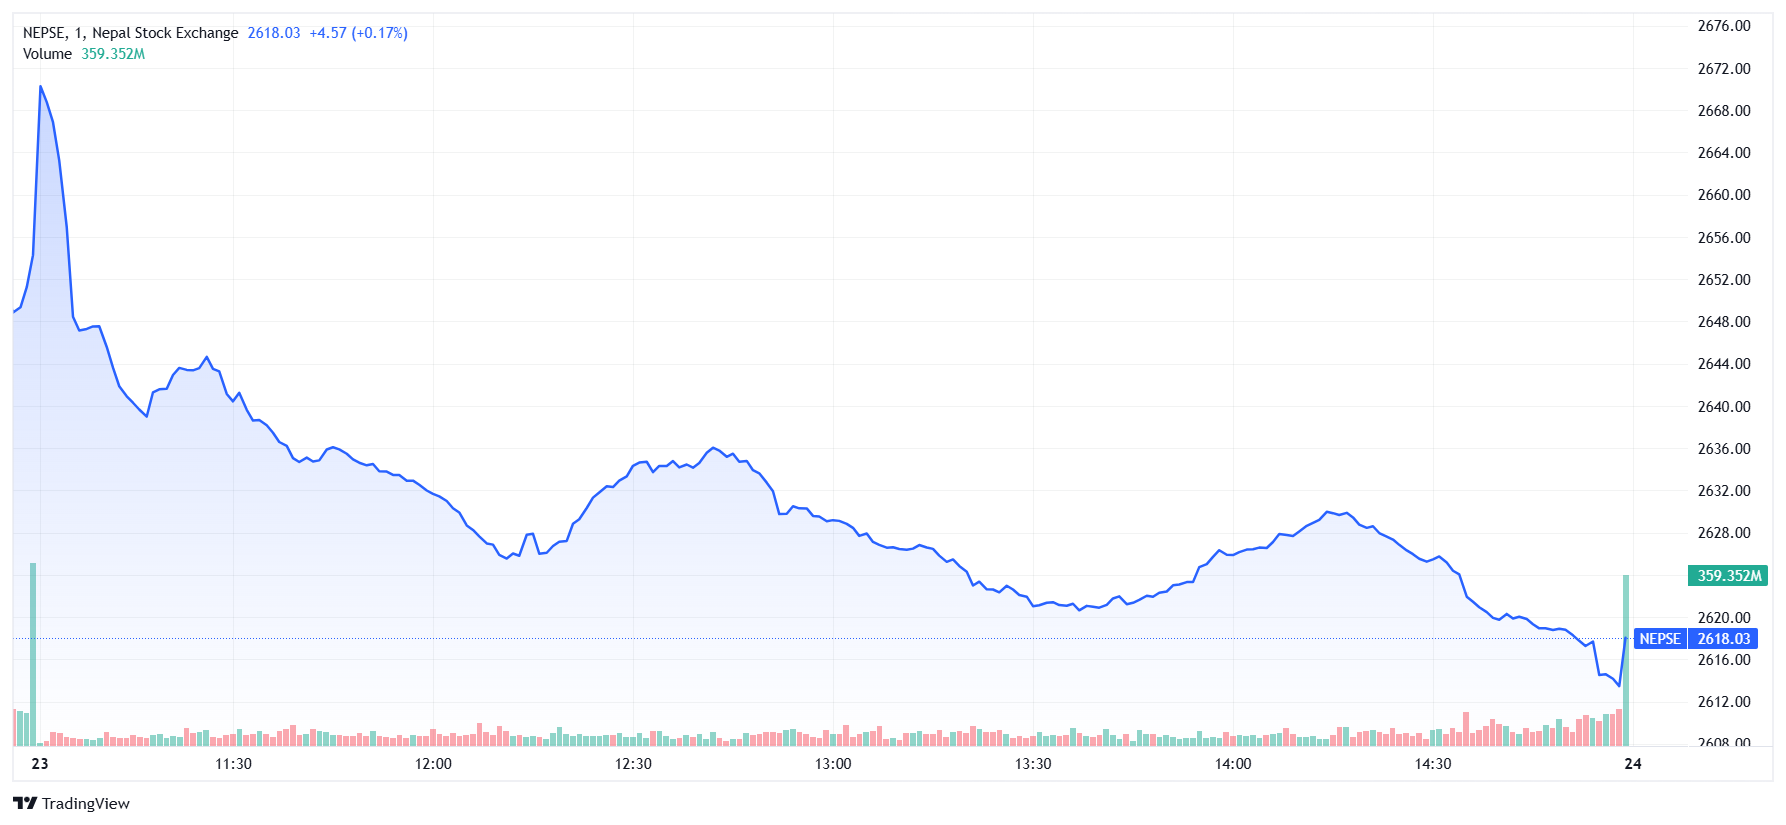
NEPSE closed 2,618.03, down 36.25 (−1.36%) the second-largest single-day decline of the coverage behind only 31 August's −43.89.
Breadth was 0.09. Twenty-three advancers against 253 decliners. That is the highest decliner count and the lowest advancer count ever recorded here, and the second-worst A/D after 31 August's 0.08.
Volume hit 2.16 crore units a new coverage high on Rs 6.36 arab of turnover. Record participation into the worst breadth day of the month. That is distribution, not a drift.
The round trip completed while this report had no data. Today's −36.25 implies a 22 September close of 2,654.28 above the 7 August starting level of 2,650.08. The market recovered the entire drawdown during the 20–22 September gap and then reversed off it.
NRB took action against six microfinance institutions. FMDBL −8.54%, KMCDB −5.26%, ILBS −3.67%; the sector closed −1.31%.
Life Insurance was the worst sector at −2.04%, five sessions after leading the market. The bank rotation of 18 September is fully reversed.
HATHY fell a fourth consecutive session to 469.00 now −23.0% from its 11 September announcement-day high, still with no published explanation.
The US announced an additional Rs 4.65 billion (4 arba) for Bhotekoshi flood recovery, and the UN Secretary-General framed Nepal's disaster as a climate crisis on the day NEA formed a committee for winter power demand.
The last edition left the index 2.86 points below the level this coverage started at, with a note that clearing 2,650.08 would put the market into territory the dataset had no reference for.
It cleared it during three sessions this report did not capture and then it broke.
NEPSE closed 2,618.03, down 36.25 points (−1.36%) on Rs 6.36 arab, 2.16 crore units and 57,947 transactions across 352 scrips. Advancers 23, decliners 253, unchanged 6 an A/D of 0.09.
Every one of those breadth numbers is a record. 253 decliners beats the 225 of 16 September. 23 advancers is the lowest count in twenty-seven captured sessions. Only the 31 August capitulation at 0.08 produced a worse ratio and that came at the bottom of a 136-point slide, not eight points from the top of a recovery.
Volume is the part that should not be glossed over. 2.16 crore units is the highest of the entire coverage, beating 18 September's 2.13 crore. Turnover of Rs 6.36 arab is third-highest. Record participation on the worst breadth reading of the month is the signature of holders leaving, not of a market drifting lower on no interest.
Every captured sector closed red — the third all-red board of the coverage, and the worst of the three. Life Insurance was hardest hit at −2.04%, with ALICL −2.87%, SRLI −2.65%, LICN −2.64%, SNLI −2.46% and HLI −2.42%. That sector led the market on 17 and 18 September at +1.08% and +1.52%. Hydropower fell 1.66%, Investment 1.49%, Development Bank 1.36%.
The bank rotation is gone. Banking closed −1.22% with NICA −2.85%, PCBL −2.69%, MBL −2.38%, NIMB −2.28%, PRVU −2.15%, NMB −2.05%, NBL −1.85%, GBIME −1.82%, LSL −1.64% and KBL −1.32%. Five sessions ago six banks occupied the volume top ten and the sector led the market at +1.59%. Today only SBL (−0.22%) and NABIL (−0.12%) held anywhere near flat. Rotation number eighteen, dead.
On the stated cause. Nepalytix headlined the session as weather concerns triggering selling pressure. This report could not verify a specific meteorological trigger in the day's feeds. What is verifiable and adjacent: the UN Secretary-General publicly framed Nepal's disaster as evidence of a growing climate crisis, and NEA formed a five-member committee to prepare for winter power demand both on the same day, both pointing at seasonal and climate risk. Treat "weather concerns" as plausible framing rather than an established driver.
Index Snapshot
NEPSE: 2,618.03, -36.25 (-1.36%)
Turnover Rs 6.36 arab
Volume 2.16 crore units (coverage high)
Transactions 57,947
Scrips traded 352
Float fell 1.42% against NEPSE's 1.36%, the float-adjusted market did slightly worse. On 18 September the same measure outperformed by a comfortable margin on the way up. The quality bid that carried last week's rally was selling today.
Sectoral Indices Performance
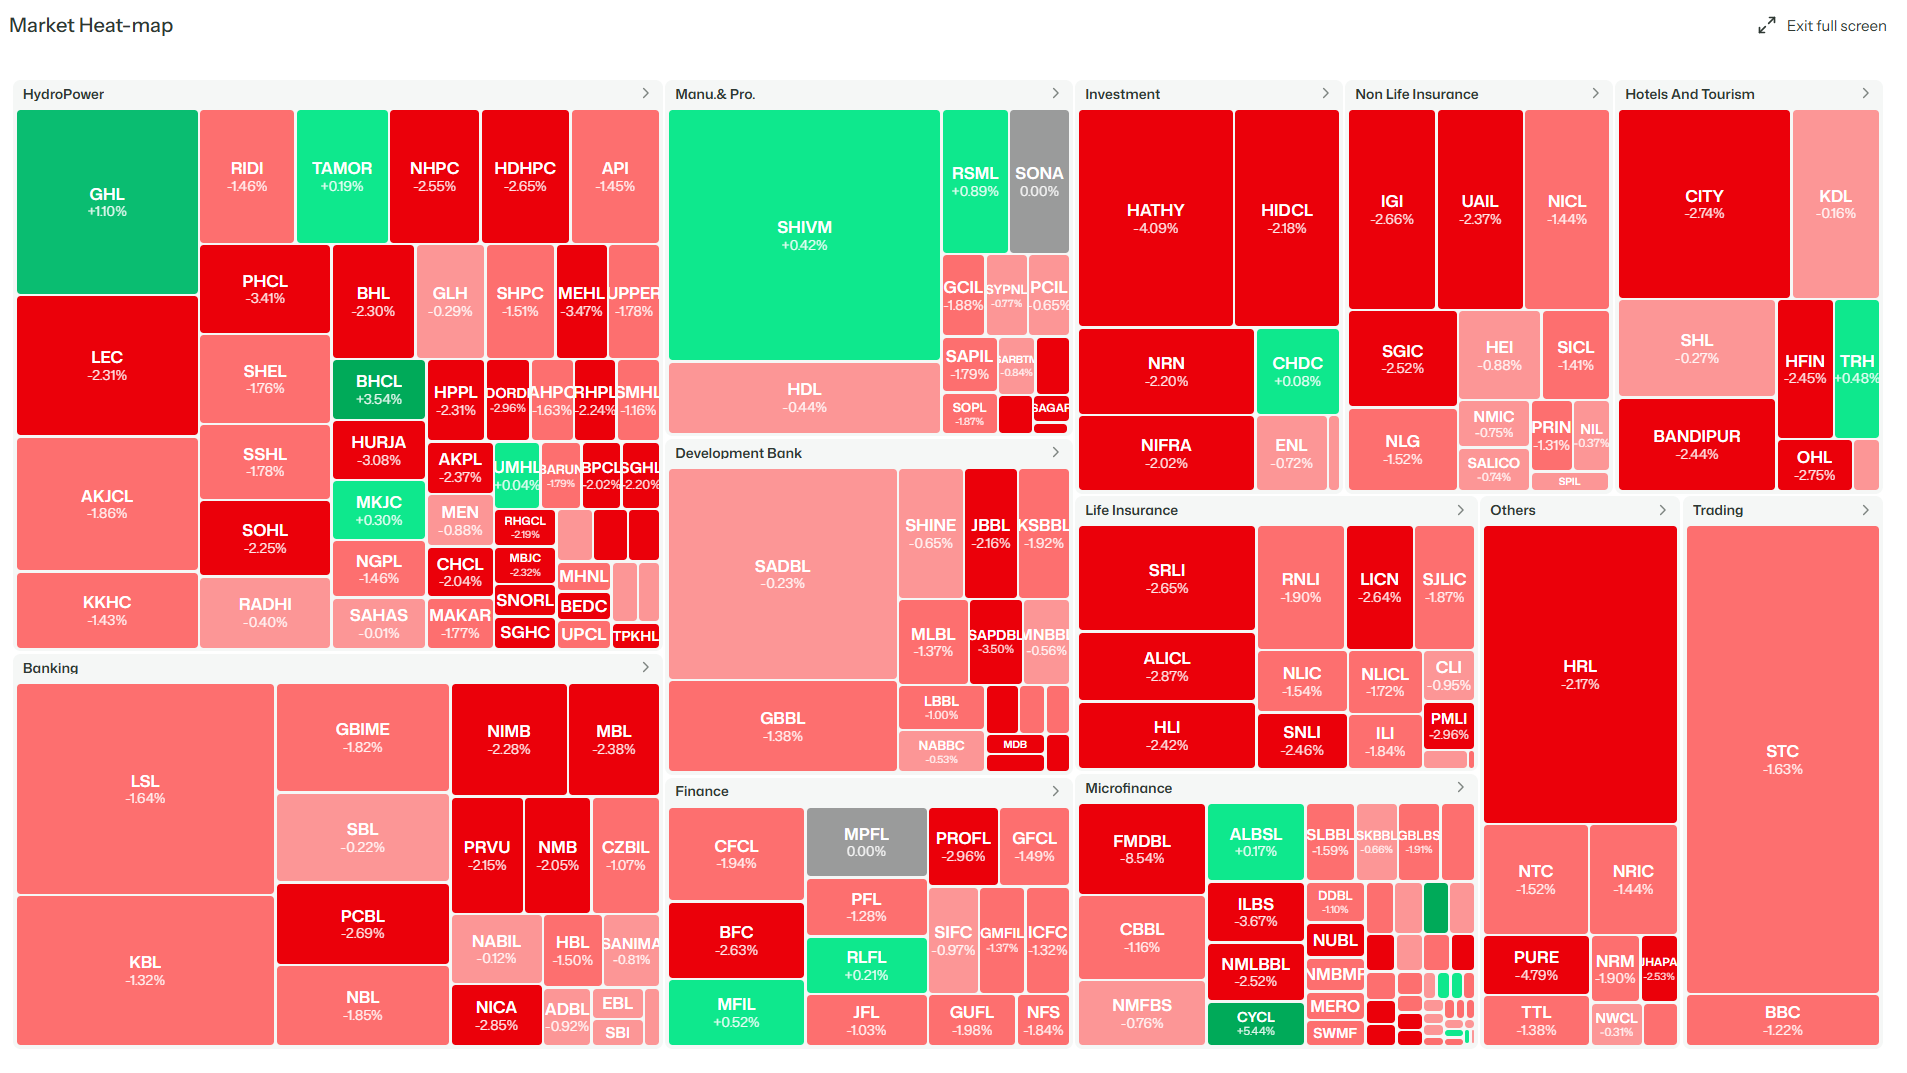
Eleven captured, all red. Float (180.39, −1.42%) is a broad index, not a sub-index. Trading is negative on STC −1.63% and BBC −1.22%; Others is negative on PURE −4.79%, HRL −2.17% and NTC −1.52%.
Manufacturing at −0.45% is the only sector that genuinely resisted, held up by SHIVM +0.42% and RSML +0.89%, the two largest turnover names in the market.
Market Breadth
Metric | Count |
|---|---|
Advancers | 23 — coverage low |
Decliners | 253 — coverage high |
Unchanged | 6 |
Live universe | 282 |
A/D ratio | 0.09 |
A/D series (last nine captured sessions): 0.34 → 7.65 → [gap] → 22.08 → 0.19 → 2.08 → 2.65 → [gap] → 0.09
Ninety per cent of the quoted universe fell. For context, the record high of 22.08 came eight sessions ago; the market has now printed 22.08, 0.19, 2.08, 2.65 and 0.09 inside two weeks. This is not a market finding a level. It is a market being repriced violently in both directions on successive sessions.
The one structural note worth carrying: 0.09 came with record volume. The 31 August reading of 0.08 came on Rs 2.91 arab, the lowest turnover of the coverage. A capitulation on no volume and a capitulation on record volume are different events. The first is exhaustion; the second is supply.
Winners & Losers
Top Gainers
Only 23 names advanced in the entire market.
Stock | Sector | LTP | % |
|---|---|---|---|
DLBS | Microfinance | 1,341.90 | +15.00% |
CYCL | Microfinance | 1,531.00 | +5.44% |
BHCL | HydroPower | 559.00 | +3.54% |
BNL | Manu. & Pro. | 14,244.70 | +3.00% |
MSHL | HydroPower | 622.00 | +2.64% |
USHL | HydroPower | 521.50 | +1.26% |
ULHC | HydroPower | 330.00 | +1.20% |
GHL | HydroPower | 257.00 | +1.10% |
RSML | Manu. & Pro. | 2,722.90 | +0.89% |
AVYAN | Microfinance | 1,059.00 | +0.83% |
DLBS closed limit-up at +15.00% on the day NRB disciplined six microfinance institutions and the sector fell 1.31%. Its recent path: 1,119 (15 Sep) → 1,248 → 1,184 → 1,341.90. That is +19.9% in five sessions in a name that appears in neither activity table. Treat it as a thin print, as this report has repeatedly done with names in this pattern.
GHL is the only gainer with genuine weight second by volume at 6.63 lakh shares and sixth by turnover at Rs 17.16 crore. RSML rose 0.89% while taking Rs 21.26 crore, second-highest turnover in the market.
Top Losers
Stock | Sector | LTP | % |
|---|---|---|---|
FMDBL | Microfinance | 750.00 | −8.54% |
MEPDL | HydroPower | 646.20 | −5.72% |
KMCDB | Microfinance | 810.00 | −5.26% |
IHL | HydroPower | 325.10 | −5.22% |
PURE | Others | 795.00 | −4.79% |
BNT | Manu. & Pro. | 11,932.00 | −4.51% |
HATHY | Investment | 469.00 | −4.09% |
ILBS | Microfinance | 968.00 | −3.67% |
TVCL | HydroPower | 296.00 | −3.58% |
SAPDBL | Development Bank | 606.00 | −3.50% |
Four of the ten worst are microfinance, on the day NRB took enforcement action against six institutions in the sector. FMDBL's −8.54% is the largest decline on the board.
HATHY fell a fourth consecutive session. The arc is now: +5.56% on 11 September on announcing up to Rs 40 crore of investment into a sugar mill and hydropower, then −2.97%, −15.00% limit-down, and −4.09% today to 469.00. From 609.00 that is −23.0% in eight sessions, still with no published explanation. This report flagged it last week as information likely not yet public; a fourth session of selling without disclosure strengthens that reading.
TVCL −3.58% to 296.00, the name carrying Rs 8.2 billion of loans on ICRA negative watch after the total loss of its 37 MW Upper Trishuli-3 'B' project. It is down roughly 10.3% from 330 since the rating action.
IHL −5.22% reverses its post-restoration bounce.
Turnover & Volume Leaders
Most Active by Turnover
Stock | LTP | % | Turnover |
|---|---|---|---|
SHIVM | 687.00 | +0.42% | Rs 38.34 Cr |
RSML | 2,722.90 | +0.89% | Rs 21.26 Cr |
HDL | 1,278.30 | −0.44% | Rs 20.54 Cr |
LSL | 245.90 | −1.64% | Rs 18.85 Cr |
AKJCL | 358.00 | −1.86% | Rs 17.30 Cr |
GHL | 257.00 | +1.10% | Rs 17.16 Cr |
SADBL | 428.00 | −0.23% | Rs 16.11 Cr |
RADHI | 717.00 | −0.40% | Rs 13.34 Cr |
LEC | 254.00 | −2.31% | Rs 13.17 Cr |
TAMOR | 534.00 | +0.19% | Rs 13.1 Cr |
Most Active by Volume
LSL (7.62 L, −1.64%), GHL (6.63 L, +1.10%), SHIVM (5.55 L, +0.42%), KBL (5.47 L, −1.32%), LEC (5.09 L, −2.31%), AKJCL (4.79 L, −1.86%), SADBL (3.72 L, −0.23%), KKHC (2.80 L, −1.43%), GBIME (2.66 L, −1.82%), RIDI (−1.46%)
SHIVM took Rs 38.34 crore, 6.0% of all turnover and closed green at +0.42% on a day 253 names fell. It is the largest single-name turnover figure since HDHPC's Rs 37.96 crore on 16 September.
Three of the top four turnover names closed green: SHIVM, RSML and, further down, GHL while the rest of the market was sold. Money concentrated defensively into a handful of Manufacturing and hydro names rather than leaving entirely.
HDL, SADBL and RADHI are new to the top ten, all roughly flat. LSL and KBL, the leaders of last week's bank rotation, were sold on heavy volume, LSL top by volume at 7.62 lakh shares, down 1.64%.
Concentration remains low by this market's standards: largest name 6.0%, top five roughly 18% of turnover.
Signal Scorecard
Prior call | Status | What happened |
|---|---|---|
"2,650.08 — 2.86 points away. Clearing it puts the index into territory this report has no data on" | CLEARED, THEN REVERSED | Implied 22 September close of 2,654.28 above the coverage start. The full round trip completed during the gap, and today gave back 36.25 points. |
"Does the bank rotation survive a second session?" | IT DIDN'T SURVIVE THE WEEK | Banking −1.22% with ten constituents down more than 1.3%. Rotation eighteen, failed. |
"Turnover at Rs 6.75 arab against the new tax — if it holds above Rs 6 arab, the tax is too small to matter" | HELD, AND VOLUME SET A RECORD | Rs 6.36 arab and 2.16 crore units, a coverage high. The 5%/3.5% advance tax has produced no visible effect on participation in five sessions. |
"HATHY — watch for a SEBON disclosure, a rating action, or a shareholder filing" | NOTHING PUBLISHED, FOURTH DECLINE | −4.09% to 469.00, −23.0% from the announcement high. Eight sessions, no explanation. |
"Remittance deceleration is the thing to watch" | NO NEW DATA | Next NRB monthly release is the trigger. Growth was 21.2% against 29.9% a year earlier; 10.2% in dollar terms against 25%. |
"Block data, two sessions missing" | THIRD SESSION MISSING | No Bulk Transaction capture again. The question of whether large holders are distributing is now unanswered for three consecutive sessions on a day volume hit a record. |
"Cash dividends 5 for 5 on the move, 0 for 5 on extending it" | MECHANICAL ADJUSTMENT | Snow Rivers and Shangrila Development Bank prices were adjusted for bonus shares today, so SNORL's +13.66% of 18 September is no longer comparable on a raw price basis. |
"The Ashwin AGM cluster is the real test" | BOOK CLOSURES ARRIVING | Five companies hit their last trading day to secure dividends today, and Citizens Bank set book closure for its 4% dividend with an AGM on Ashwin 28. |
Top Stories
1. NRB disciplines six microfinance institutions and the sector's worst names led the fall
Nepal Rastra Bank has taken action against six microfinance institutions.
The tape responded immediately and specifically. Four of the day's ten worst performers are microfinance: FMDBL −8.54% (the largest decline on the board), KMCDB −5.26%, ILBS −3.67%, and NMLBBL −2.52%. The sector index closed −1.31%.
Why it matters. This report has documented microfinance dispersion for three weeks, the sector routinely producing three of the top gainers and three of the top losers on the same day, with the index carrying no information. Today the dispersion has a regulatory cause rather than being thin-print noise.
It also lands on a sector already under structural pressure. Microfinance sits at the end of the credit chain this report has tracked: Rs 166.50 billion of margin lending, NRB withdrawing Rs 85 billion from BFIs, a reconstruction bill near NPR 560 billion, and still no NRB circular on flood-affected loan classification. Microfinance borrowers in flood-hit districts are the least able to absorb any of it.
Watch for the names, the nature of the action and whether any of the six are listed. Enforcement against six institutions at once is a supervisory sweep, not an isolated penalty.
2. The US puts Rs 4.65 billion into Bhotekoshi recovery and the UN calls it climate
The United States announced an additional 4 arba roughly Rs 4.65 billion in aid for Nepal's Bhotekoshi flood recovery. On the same day, UN Secretary-General António Guterres framed Nepal's disaster as a reflection of the growing climate crisis.
Why it matters. Set the aid against the arithmetic this report has carried: reconstruction estimated near NPR 560 billion ($4 billion), hydro investment-value damage around NPR 180 billion, insurance claims filed of NPR 25.87 billion, and a Gen-Z settlement precedent running at 32.4%. Adding the ADB's earlier $5 million grant, external assistance now totals roughly Rs 5.3 billion — under 1% of the reconstruction estimate.
The gap is not closing, and the fiscal position is not improving. Government revenue is at 11.59% of annual target after two months. Rasuwagadhi remains shut with customs there, roughly NPR 13.64 billion annually, impaired. The merchandise trade deficit widened 24.9% to Rs 148.74 billion in the first month of the fiscal year.
The UN framing matters for a different reason. Nepal's hydropower sector is the collateral in this market every listed generator, the Rs 115 billion committed to Tila-1 and Tila-2, and NEA as universal offtaker with a 43% profit decline. A disaster reclassified as recurring climate risk rather than a one-off event changes the insurance and financing cost of every future project. The government's integrated climate-resilience plan for hydropower, announced 11 September, is the policy side of the same recognition.
3. NEA prepares for winter power while importing 654 MW
NEA has formed a five-member committee to prepare for winter power demand.
Why it matters, and why the timing is awkward. Winter is Nepal's low-generation season run-of-river plants which are most of the listed sector, produce a fraction of monsoon output. This year NEA enters that season with twelve projects still offline from the Bhotekoshi flood, exports down from roughly 1,000 MW to 650 MW and India having approved up to 654 MW of supply to Nepal for 18 hours daily.
A country that was a net electricity exporter earning roughly NPR 19.97 billion is heading into winter as a structural importer with NEA already reporting a 43% profit decline carrying the cost. Hydropower closed −1.66% today, the second-worst sector.
4. Book closures arrive and the tax meets its first real test
Five companies reached their last trading day to secure dividends today. Separately, Citizens Bank International set the book closure date for its 4% dividend and called its AGM for Ashwin 28.
Why it matters. The new advance tax, 5% on holdings of 365 days or less, 3.5% beyond, collected at source by NEPSE creates a 150 basis point incentive to hold through book closure rather than trade around it. This report has tracked cash dividends as 5 for 5 on producing an announcement-day move and 0 for 5 on extending it meaning holders have historically sold into the announcement.
Today is the first session where book closures and the new tax coincide, and the broader tape was down 1.36% with 253 decliners, which makes clean attribution impossible. The cluster still to come is the test: GBIME and KDL on Ashwin 16, Nabil Investment Banking on Ashwin 20, Reliance Spinning's 30% cash on Ashoj 22, Citizens Bank on Ashwin 28.
One mechanical note that matters for anyone tracking prices: Snow Rivers and Shangrila Development Bank had their share prices adjusted for bonus shares today. SNORL's +13.66% of 18 September is no longer comparable on a raw basis.
5. New paper: two mutual funds and a debenture
The public issue of the NIC ASIA Equity Opportunity Fund opened today. Muktinath Capital extended the application deadline for Muktinath Mutual Fund 2 to Ashwin 15. And "7% Laxmi Sunrise Debenture 2092 (LSD92)" was listed on NEPSE.
Why it matters. Two equity mutual fund issues open simultaneously pull subscription money out of the secondary market during the application window, the same mechanic flagged when Beni Hydropower's IPO drew 1.16 million applicants against roughly 1.7 million active demat accounts. A deadline extension on Muktinath Mutual Fund 2 also suggests the raise is not filling easily.
The debenture listing is the other side of the liquidity story. A 7% coupon against a one-year fixed deposit at roughly 4.55% and savings at 2.9% is a meaningfully better risk-adjusted return than a deposit and it is exactly the bond-market development SEBON described as a priority on 7 September. Watch whether more corporate debentures list; they compete directly for the deposit money that has been funding this equity rally.
6. Minister floats a 2% hydropower IPO quota for security personnel
A minister has proposed reserving 2% of hydropower IPOs for security personnel.
Why it matters: Nepal's primary market already allocates quotas to various groups, and every carve-out reduces the pool available to the general public in issues that are running 15.80 times oversubscribed. It is small in itself but it is the second policy proposal in a month aimed at the primary market's allocation mechanics SEBON's stated priority is genuine price discovery through qualified institutional investors, and quota expansion moves in the opposite direction.
7. Diplomacy, aviation and the corporate board
Foreign Minister Khanal held talks with India's External Affairs Minister Jaishankar, the second senior Nepal-India engagement this month after Finance Minister Wagle's Delhi visit, with power trade and reconstruction financing the obvious agenda. Nepal formally established diplomatic relations with Grenada.
Flydubai began regular commercial flights between Pokhara and Dubai today: the first direct international scheduled service from Pokhara International Airport, an asset that has been criticised for underuse since opening. Hotels & Tourism closed −0.98%, but this is a structural positive for CITY, TRH and SHL heading into the season.
Nepal Bank deposited Rs 84.20 lakh of employee contributions to the Disaster Relief Fund. Kamana Sewa installed public waiting benches in Kumaripati-Jawalakhel. Kajaria Ramesh Tiles expanded its dealer network. Sipradi delivered 150 Tata vehicles on Vishwakarma Puja. The Nepalgunj Land Revenue Office collected Rs 74.86 crore in FY 2082/83.
Corporate Actions & Events
Company | Action | Detail |
|---|---|---|
Six microfinance institutions | Regulatory | NRB enforcement action, FMDBL −8.54%, KMCDB −5.26%, ILBS −3.67% |
Snow Rivers / Shangrila Dev. Bank | Price adjustment | Adjusted for bonus shares prior prices not comparable |
Citizens Bank (CZBIL) | Book closure | 4% dividend, AGM Ashwin 28 |
Five companies | Book closure | Last trading day to secure dividends today |
NIC ASIA Equity Opportunity Fund | Mutual fund | Public issue opened today |
Muktinath Mutual Fund 2 | Mutual fund | Deadline extended to Ashwin 15 |
Laxmi Sunrise (LSD92) | Debenture | 7% debenture 2092 listed on NEPSE |
Reliance Spinning Mills | Dividend | 30% cash book closure set, AGM Ashoj 22 |
Nabil Investment Banking | Dividend | 10% bonus + 11.05% cash, AGM Ashwin 20 |
Global IME Bank (GBIME) | Dividend | 10% (4% bonus + 6% cash), AGM Ashwin 16 |
Kalinchowk Darshan (KDL) | Dividend | 8.9474%, AGM Ashwin 16, shareholders selling |
Siddhartha Bank (SBL) | Dividend | 20% proposed |
Sarvottam Paints | Dividend | 10% proposed, 5th AGM |
Global IME Balanced Fund-1 | Book closure | 12% cash dividend |
Trishuli Jal Vidyut (TVCL) | Rating | Rs 8.2 bn loans on NEGATIVE WATCH , stock −3.58% today |
Sagarmatha Jalabidhyut | Rating | BBB-, Watch with Negative Implication |
Himalayan Reinsurance (HRL) | Board | Chair still vacant: −2.17% today |
Emerging Nepal (ENL) | Shareholder sales | 7 holders, 913,099 shares |
Upper Hewakhola (UHEWA) | Shareholder sales | Two holders, 134,601 shares |
— | Policy | 2% hydropower IPO quota for security personnel proposed |
— | Tax | Advance tax on securities gains: 5% ≤365 days, 3.5% >365 days, at source |
What to Watch
1. 2,600, then 2,594. Eighteen and twenty-four points below. 2,594 is the first genuinely tested level underneath. The market has twice this month broken a support on first test 2,550 on 9 September and 2,542.77 on 10 September so a clean hold at 2,600 would be a change of behaviour rather than a continuation.
2. Record volume into the worst breadth of the month. 2.16 crore units with 253 decliners. If tomorrow brings a second heavy-volume decline, this is a distribution phase rather than a single bad session. Watch the volume figure before the index figure, a lower-volume decline would suggest supply is clearing.
3. The six microfinance institutions. Watch for the names and the nature of NRB's action, and whether any are listed. FMDBL, KMCDB and ILBS took the heaviest hits today; a supervisory sweep usually produces follow-on disclosures within days.
4. HATHY eight sessions, −23.0%, still nothing published. A fourth consecutive decline with no SEBON filing, rating action or shareholder disclosure. The ENL precedent price collapsing two sessions before the filing appeared argues this is unpublished information rather than sentiment.
5. Book closure behaviour against the new tax. Five companies passed their last dividend-securing day today, with the Ashwin cluster still ahead: GBIME and KDL on the 16th, Nabil Investment Banking on the 20th, Reliance Spinning on Ashoj 22, Citizens Bank on the 28th. With short-term gains taxed 150bp higher, the question is whether holders sit through book closure instead of selling into the announcement. Five for five on announcement moves, zero for five on extending them, that is the record to break.
6. Block data, now three sessions dark. No Bulk Transaction capture on 17, 18 or 23 September. With volume at a coverage high and breadth at 0.09, the block tape is the single most valuable missing input. The last reading, 16 September, showed MEN at Rs 3.14 crore and two of the three largest blocks arriving on falling prices.
7. Winter generation against 654 MW of imports. NEA's committee, twelve projects offline, and a low-water season beginning. Watch for a restoration timeline on RHPL, CHCL or the 220 kV Trishuli-3 'B' substation still absent after four weeks and for any NEA statement on import costs.
8. The mutual fund issues. NIC ASIA Equity Opportunity Fund opened today; Muktinath Mutual Fund 2 extended its deadline to Ashwin 15. Both absorb subscription money during their windows. A 7% Laxmi Sunrise debenture now listed against a 4.55% one-year FD is the more interesting competitor, corporate paper at that coupon draws directly on the deposit surplus funding this equity market.
Disclaimer
This report has been prepared by Nepalytix for informational and educational purposes only and does not constitute investment advice, an offer, or a solicitation to buy or sell any securities.
The information contained in this report is based on sources believed to be reliable; however, Nepalytix does not guarantee its accuracy, completeness, or timeliness. Opinions, estimates, and projections expressed herein are those of the authors as of the date of publication and are subject to change without notice.
Investing in securities involves risks, including the possible loss of principal. Past performance is not indicative of future results. Readers are advised to conduct their own independent research and consult with a qualified financial advisor before making any investment decisions.
Nepalytix and its contributors may hold positions in the securities discussed in this report at the time of publication or thereafter.
Neither Nepalytix nor any of its affiliates accept any liability for any loss arising from the use of this report or its contents.